RAIF vs SIF: Choosing the right Luxembourg alternative fund regime
Executive summary
For sponsors, family offices and private investors, the choice between a RAIF and a SIF is less a theoretical legal question than a practical structuring decision. Relevant considerations include the speed of launch, the importance of direct CSSF supervision, the role of an authorized AIFM and the extent to which each regime supports the proposed investment strategy.
The comparison should not be reduced to “regulated SIF” versus “faster RAIF”. A RAIF may operate as a SIF-like RAIF, with broad investment flexibility and risk-spreading, or as a SICAR-like RAIF, where it elects the risk-capital regime. A SIF, by contrast, remains a CSSF-regulated fund and may, in certain family office, club-deal or co-investment situations, be relevant where the structure can be organised without an AIFM.
The real decision tree is therefore not simply RAIF versus SIF. It is whether the project calls for a regulated SIF, a SIF-like RAIF or a SICAR-like RAIF, taking into account timing, investor expectations, tax treatment, the need for an authorised AIFM and the nature of the proposed investment strategy.
1.The core choice: SIF, SIF-like RAIF or SICAR-like RAIF
Luxembourg offers a wide choice of alternative investment fund vehicles. For many clients, the practical choice is between a Specialised Investment Fund (SIF) and a Reserved Alternative Investment Fund (RAIF). Both are reserved to well-informed investors and can be used for a broad range of alternative strategies, including private equity, real estate, infrastructure, private credit and other private market investments.
The RAIF, however, should not be viewed as a single standard product. In its ordinary form, it operates as a SIF-like RAIF: it offers broad investment flexibility, is generally subject to risk-spreading requirements and benefits from the subscription tax regime. Where it elects the risk-capital regime, the RAIF becomes closer to a SICAR logic. This SICAR-like RAIF may be particularly relevant for private equity, venture capital, growth capital and similar risk-capital strategies.
Different investment strategies may lead to different answers. A diversified alternative investment strategy, for example, may point towards a SIF or a SIF-like RAIF, whereas a pure risk-capital strategy may justify considering a SICAR-like RAIF.
The first question is therefore not simply whether to choose a RAIF or a SIF. Rather, it is whether the project is best served by a regulated SIF, a flexible SIF-like RAIF or a SICAR-like RAIF tailored to risk-capital investments.
2. The key distinction: CSSF product supervision or authorised AIFM
The most important practical distinction between the SIF and the RAIF is the allocation of regulatory oversight.
A SIF is a regulated fund product. It requires prior CSSF authorisation and remains subject to CSSF supervision during its life. This regulatory label may be attractive where investors, family members, investment committees or counterparties attach importance to direct regulatory oversight of the vehicle itself.
A RAIF is different. It is not authorised or supervised by the CSSF as a product, but it must always be managed by an authorised AIFM. This makes the RAIF attractive where the sponsor values speed to market and is comfortable relying on the governance, risk management and regulatory framework of the authorised AIFM.
This distinction may be particularly relevant for family offices, high-net-worth individuals and small groups of co-investors. In certain family, club-deal or co-investment structures, a SIF may allow the parties to consider a structure without an authorised AIFM, provided the relevant AIFMD analysis supports that conclusion. A RAIF does not offer that flexibility: it is always an AIF and must be managed by an authorised AIFM.
3. Which vehicle for which situation?
The choice will usually depend on the profile of the investors, the investment strategy, the desired launch timetable and the level of regulatory involvement appropriate for the project. The following table summarises the main practical considerations.
| Situation | Vehicle usually worth considering | Why it may be appropriate |
| Fast launch with an authorised AIFM already available | RAIF | No prior CSSF product approval; the AIFM provides the regulatory framework. |
| Investors expect direct CSSF supervision | SIF | The fund itself is authorised and supervised as a regulated product. |
| Family office, club deal or limited co-investment structure | SIF, depending on the AIFMD analysis | May allow a regulated Luxembourg fund structure with a more proportionate management set-up where no authorised AIFM is required. |
| Diversified alternative strategy | SIF or SIF-like RAIF | Both can offer broad investment flexibility; the choice turns on supervision, timing and investor expectations. |
| Private equity, venture capital or growth capital strategy | SICAR-like RAIF, SIF or SICAR | If the strategy is genuinely risk-capital focused, the SICAR-like RAIF may provide a more suitable tax and legal profile. |
| Need for future compartments or structural changes | RAIF | Greater operational flexibility because changes do not require prior CSSF product approval |
4. Practical takeaway
For clients, the choice should start with a simple question: what does the structure need to achieve in practice? If speed, flexibility and an authorised AIFM are already part of the model, a RAIF will often be attractive. If a CSSF-regulated product is important, or if the structure involves a limited family or co-investment circle where an authorised AIFM may not be required, a SIF may deserve closer consideration.
For private equity or venture capital strategies, the analysis should go one step further. A RAIF may be structured as a SICAR-like RAIF where the fund elects the risk-capital regime. In that case, the comparison is not only between RAIF and SIF, but between a SIF, a SIF-like RAIF and a SICAR-like RAIF.
5. Conclusion
There is no universal answer to the RAIF versus SIF question. The appropriate choice depends on the sponsor’s objectives, the investor base, the desired regulatory profile, timing considerations, tax treatment and whether an authorised AIFM is required or desirable.
The key point is to avoid an overly binary analysis. The decision is not simply whether to choose a RAIF or SIF. Rather, it is whether the project is best served by a CSSF-regulated SIF, a flexible SIF-like RAIF or, for qualifying risk-capital strategies, a SICAR-like RAIF.
Sources
Legislation
(1) Law of 23 July 2016 on Reserved Alternative Investment Funds (RAIF Law), as amended.
(2) Law of 13 February 2007 relating to Specialised Investment Funds (SIF Law), as amended.
(3) Law of 12 July 2013 on Alternative Investment Fund Managers (AIFM Law), as amended.
(4) Directive 2011/61/EU of the European Parliament and of the Council of 8 June 2011 on Alternative Investment Fund Managers (AIFMD).
Parliamentary Works
(5) Bill of Law No. 6929 introducing the Reserved Alternative Investment Fund (RAIF), including the Explanatory Memorandum.
(6) Bill of Law No. 6471 implementing Directive 2011/61/EU on Alternative Investment Fund Managers, including the Explanatory Memorandum.
Brochures
(7) Comparison table of Luxembourg private wealth vehicles: Download here
(8) Luxembourg RAIF (reserved alternative investment fund): Download here

The Luxembourg RAIF at 10: From regulatory innovation to a cornerstone of Luxembourg's Alternative Investment Funds industry
I. Introduction: More than a decade of legislative success
Few legislative initiatives have had as profound an impact on Luxembourg’s investment funds industry as the introduction of the Reserved Alternative Investment Fund (“RAIF”) by the Law of 23 July 2016 (the “RAIF Law”).
Conceived in the aftermath of the Alternative Investment Fund Managers Directive (“AIFMD”), the RAIF represented a fundamental shift in the way alternative investment funds could be structured in Luxembourg. Rather than creating another regulated investment product, the Luxembourg legislator introduced a vehicle that recognised a changing reality: for sophisticated investors, robust governance is primarily achieved through the supervision of the investment manager and the broader operational ecosystem surrounding the fund, rather than through prior approval of each individual investment vehicle.
Ten years later, that vision has proved remarkably prescient.
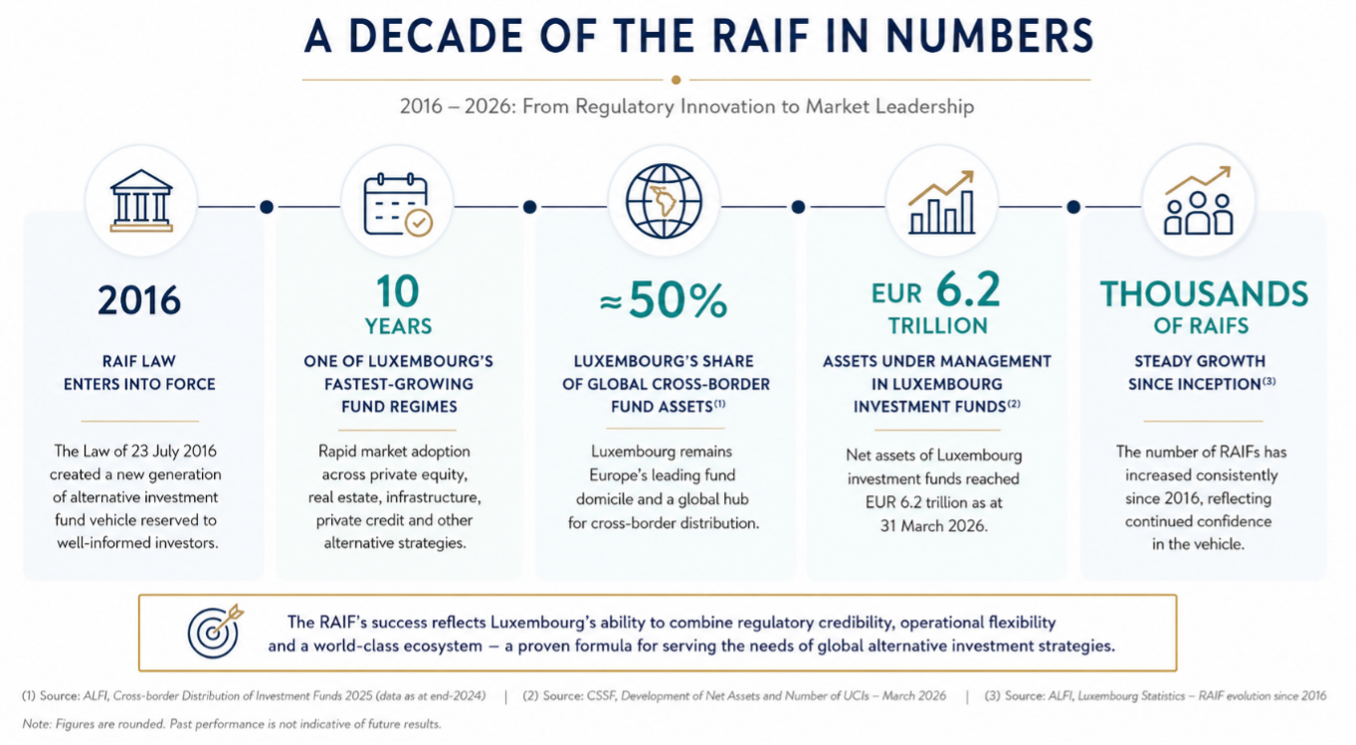
The market’s response illustrates the extent to which Luxembourg’s strategic choice has resonated with international asset managers. Luxembourg remains Europe’s leading investment fund domicile and continues to account for approximately half of global cross-border investment fund assets, reflecting the jurisdiction’s central role in international fund distribution.
The RAIF has contributed to this success. Since its introduction in 2016, the number of RAIFs has grown steadily, confirming their rapid adoption across a broad spectrum of alternative investment strategies. According to ALFI, the vehicle has established itself as one of the fastest-growing segments of Luxembourg’s alternative investment fund market.
The RAIF has become an integral component of Luxembourg’s alternative investment funds framework and is now routinely used across private equity, real estate, infrastructure, private credit, venture capital and other private market strategies. It has equally demonstrated considerable adaptability, increasingly being considered by entrepreneurial groups and family offices seeking institutional governance standards while preserving structuring flexibility.
Its success cannot be explained solely by the absence of prior CSSF approval. Nor should it be viewed simply as a faster alternative to existing regulated vehicles.
The RAIF’s enduring appeal lies in a carefully calibrated balance between flexibility and regulatory credibility. It combines the contractual freedom expected by sophisticated sponsors with the safeguards of the AIFMD framework through the mandatory appointment of an authorised Alternative Investment Fund Manager (“AIFM”) and the involvement of regulated service providers. In doing so, it reflects a broader evolution in European financial regulation: a shift away from product-centric supervision towards oversight centred on the entities responsible for investment management.
A decade after its introduction, the RAIF is no longer an innovative newcomer. It has become part of the infrastructure of Luxembourg’s alternative investment ecosystem.
This article revisits the legislative rationale behind the creation of the RAIF, analyses the regulatory philosophy that underpins its success and explores why it continues to occupy a central position in the structuring of alternative investment funds for asset managers, institutional investors and increasingly sophisticated private wealth.
II. Why Luxembourg needed the RAIF
The creation of the RAIF was not an isolated legislative initiative. It formed part of a broader transformation of the European regulatory landscape following the global financial crisis and the implementation of the AIFMD.
By introducing a harmonised regulatory framework for alternative investment fund managers, the AIFMD fundamentally altered the organisation of the European alternative investment industry. Rather than harmonising every type of alternative investment fund, the Directive focused on the prudential regulation of the manager responsible for portfolio management, risk management and investor protection.
Luxembourg implemented this framework through the Law of 12 July 2013 on Alternative Investment Fund Managers, while preserving its well-established range of domestic investment vehicles. As a result, Luxembourg sponsors continued to benefit from structures such as the Specialised Investment Fund (“SIF”) and the Investment Company in Risk Capital (“SICAR”), both of which remained subject to direct product supervision by the Commission de Surveillance du Secteur Financier (“CSSF”).
In practical terms, the RAIF borrowed many of the structuring features that had made the SIF and, for risk capital strategies, the SICAR attractive to international sponsors, while removing the requirement for prior CSSF approval at product level. Like the SIF, it offers broad investment flexibility and may be reserved to sophisticated investors; unlike the SIF and the SICAR, however, it is not itself authorised and supervised as a regulated product by the CSSF. This distinction allowed Luxembourg to preserve a familiar fund architecture while materially improving time-to-market for well-informed investors.
Although this model offered a high level of regulatory oversight, it also resulted in a dual supervisory framework. The authorised AIFM was subject to ongoing prudential supervision under the AIFMD, while the investment vehicle itself generally remained subject to prior authorisation and continuing product supervision by the CSSF.
The Luxembourg legislator identified an opportunity to modernise this approach.
The legislative preparatory works (travaux préparatoires) to the RAIF Law make clear that this dual supervision did not result from any requirement imposed by European law. Instead, it reflected Luxembourg’s domestic regulatory choices. The legislator therefore sought to introduce a new investment vehicle capable of preserving the high standards of investor protection associated with Luxembourg funds while eliminating an additional layer of product supervision that was no longer considered indispensable for well-informed investors.
The objective was not deregulation. It was regulatory efficiency.
Rather than reducing investor safeguards, the RAIF reallocates them. Regulatory oversight is exercised primarily through the authorised AIFM, which remains responsible for complying with the comprehensive organisational, operational and conduct of business requirements imposed by the AIFMD. The fund itself operates within this broader regulatory framework while remaining outside the scope of direct prudential supervision as a product by the CSSF.
This legislative choice also responded to increasingly competitive international markets.
Alternative asset managers were seeking investment vehicles capable of being established within commercially driven transaction timetables while continuing to benefit from a recognised European regulatory framework. Luxembourg’s challenge was therefore not simply to create another investment vehicle, but to reinforce its competitiveness as a leading domicile for alternative investment funds without compromising its reputation for legal certainty, governance and investor protection.
The RAIF successfully reconciled those objectives. It preserved the credibility associated with Luxembourg’s investment fund industry while offering sponsors significantly greater flexibility in establishing new investment structures.
Importantly, the RAIF was never intended to become a retail investment product. It remains reserved to “well-informed investors”, reflecting the legislator’s assessment that institutional investors, professional investors and other sufficiently experienced investors are capable of evaluating the risks associated with alternative investment strategies without requiring direct product supervision by the CSSF.
III. A regulatory innovation rather than regulatory simplification
The RAIF is frequently described as a fund that is “not supervised by the CSSF”. Although technically accurate in relation to product approval, this description risks oversimplifying one of the most significant innovations introduced by the RAIF Law.
The RAIF did not remove regulation.
It reorganised it.
Prior to 2016, Luxembourg alternative investment structures frequently combined supervision of both the investment vehicle and the investment manager. The RAIF introduced a different allocation of regulatory responsibilities, recognising that the AIFMD had already established a comprehensive supervisory framework centred on the authorised AIFM.
This distinction remains fundamental.
The authorised AIFM is responsible for portfolio management, risk management, valuation oversight, conflicts of interest, remuneration policies, transparency obligations and regulatory reporting. Depending on the characteristics of the structure, the RAIF must also appoint the service providers required under the applicable legal framework, including a depositary, a central administration and an approved statutory auditor.
Investor protection therefore results from the interaction of a comprehensive governance ecosystem rather than from direct supervision of the investment vehicle itself.
In retrospect, this approach anticipated a broader evolution within the alternative investment industry.
Institutional investors increasingly assess investment structures by reference to the quality of governance, the experience of the investment manager, operational resilience, transparency and alignment of interests. Product approval, while remaining relevant for many categories of investment funds, is no longer viewed as the sole or even the principal indicator of investor protection for sophisticated alternative investment strategies.
The RAIF reflects this reality. It acknowledges that, for well-informed investors, confidence derives less from the existence of an additional regulatory authorisation than from the quality of the regulatory framework surrounding the investment manager and the broader investment platform.
This shift in regulatory philosophy arguably represents the RAIF’s greatest contribution to Luxembourg investment fund law. Rather than weakening regulation, it demonstrated that investor protection and operational efficiency are not mutually exclusive objectives. By placing the authorised AIFM at the centre of the supervisory framework, while preserving robust governance standards and the involvement of regulated service providers, Luxembourg introduced a model that has proven both resilient and commercially successful.
Ten years later, this architecture continues to distinguish the RAIF from many competing investment vehicles and remains one of the principal reasons for its enduring relevance within the European alternative investment industry.
IV. Why the RAIF became the vehicle of choice
Legislative innovation alone does not explain the RAIF’s success. Over the past decade, the vehicle has become firmly established because it addresses the practical requirements of sponsors operating in increasingly competitive private markets.
Fundraising processes have accelerated, transactions have become more complex and investors expect institutional governance combined with efficient execution. Against this backdrop, the RAIF has emerged as a structuring solution capable of reconciling these objectives without departing from the regulatory framework established by the AIFMD.
Efficient execution in a competitive market
One of the principal attractions of the RAIF is the absence of prior product authorisation by the CSSF.
Unlike regulated fund regimes requiring approval before launch, a RAIF may generally be established once the constitutional documents have been finalised and the required service providers have been appointed. This allows sponsors to align the establishment of the vehicle more closely with commercial fundraising and transaction timelines.
For private equity sponsors, infrastructure managers and real estate investors operating in competitive acquisition processes, this operational flexibility may represent a significant advantage. It enables the legal structure to adapt to commercial opportunities rather than requiring commercial opportunities to adapt to regulatory approval processes.
This should not, however, be confused with the absence of regulation. The regulatory obligations applicable to the authorised AIFM, together with the involvement of the other required service providers, continue to provide the governance framework expected by sophisticated investors.
Flexibility across strategies and legal forms
Another distinguishing characteristic of the RAIF is its adaptability.
The vehicle may be established using a broad range of Luxembourg legal forms, including corporate entities and limited partnerships, allowing sponsors to select the governance model most appropriate for their investment strategy and investor base.
Similarly, the RAIF may operate as an umbrella structure with multiple compartments whose assets and liabilities remain legally segregated. This enables managers to accommodate different investment strategies, investor groups, geographical focuses or investment vintages within a single legal framework while maintaining operational efficiency.
Rather than imposing a single model, the RAIF provides a framework capable of adapting to the commercial realities of different alternative investment strategies.
A recognised European platform
The RAIF also benefits from being embedded within Luxembourg’s broader investment fund ecosystem.
This ecosystem has continued to expand over the past decade. According to the CSSF, Luxembourg investment funds held more than EUR 6.6 trillion in net assets as at 31 May 2026, underlining the scale and maturity of the jurisdiction’s fund industry.
The jurisdiction combines a mature legal framework with an extensive network of authorised AIFMs, depositaries, central administrators, auditors and specialist advisers. This operational infrastructure has contributed significantly to Luxembourg’s position as one of the world’s leading cross-border investment fund domiciles and provides sponsors with a high degree of familiarity among institutional investors, financing providers and international counterparties.
In practice, sponsors are not simply selecting a legal vehicle. They are choosing an ecosystem capable of supporting increasingly sophisticated investment structures throughout their lifecycle.
Beyond launch: supporting the entire investment lifecycle
The RAIF has demonstrated its ability to support investment structures well beyond their initial fundraising phase.
Over the past decade, sponsors have increasingly used RAIFs not only for flagship funds but also for parallel vehicles, co-investment arrangements, continuation funds, warehousing structures and other bespoke investment platforms designed to respond to evolving investor requirements.
Its contractual flexibility allows governance and economic arrangements to be tailored to the specific needs of each transaction while maintaining the consistency and legal certainty expected by institutional investors.
Ultimately, the market has embraced the RAIF because it is not merely quicker to establish. It provides sponsors with a flexible legal framework capable of evolving alongside increasingly sophisticated investment strategies while remaining anchored within a recognised European regulatory environment.
V. The RAIF today: Supporting the evolution of private markets
The alternative investment industry of 2026 bears little resemblance to that of 2016.
Private markets have expanded considerably beyond their traditional focus on buyout transactions and real estate investments. Institutional investors now allocate capital across infrastructure, renewable energy, private credit, venture capital, digital infrastructure and numerous other specialised strategies. At the same time, investment structures themselves have become increasingly sophisticated.
One of the RAIF’s greatest strengths has been its capacity to evolve alongside these developments. Market data also illustrates the continuing expansion of the vehicle. ALFI’s industry statistics show a sustained increase in the number of RAIFs since the regime was introduced in 2016, reflecting the vehicle’s growing acceptance among international sponsors across multiple alternative asset classes.
From flagship funds to bespoke investment platforms
While the RAIF continues to be widely used for traditional private equity and real estate funds, its application has expanded significantly over the past decade.
Sponsors now regularly use RAIFs to establish co-investment vehicles alongside flagship funds, continuation vehicles in GP-led transactions, dedicated sector-focused investment platforms, feeder structures and parallel funds designed to accommodate different categories of investors.
Rather than requiring a separate legal framework for each of these structures, the RAIF provides sufficient flexibility to support a broad range of investment solutions within a familiar Luxembourg environment.
Accommodating new investment strategies
The diversification of private markets has also broadened the range of asset classes commonly structured through RAIFs.
Infrastructure investments often require long-term governance arrangements and cross-border holding structures. Private credit strategies may involve increasingly sophisticated financing transactions. Venture capital funds require flexibility throughout successive fundraising rounds, while digital infrastructure and energy transition investments frequently combine assets located across several jurisdictions.
The RAIF’s legal framework is sufficiently adaptable to accommodate these diverse investment strategies while maintaining a consistent governance model centred on the authorised AIFM.
Governance has become a competitive advantage
Perhaps the most significant evolution over the past decade concerns investor expectations.
Institutional investors now devote considerable attention to operational due diligence, governance arrangements, conflicts management, valuation procedures, cybersecurity, sustainability-related governance and regulatory compliance. The quality of an investment platform is therefore measured not only by its investment performance but also by the robustness of its governance framework.
In this environment, the RAIF’s architecture has proved particularly resilient. By combining operational flexibility with institutional governance standards, it continues to meet the expectations of increasingly sophisticated investors without requiring fundamental legislative reform.
Its success demonstrates that flexibility and investor confidence are not opposing objectives. Properly designed governance may enhance both.
VI. Family offices: A new frontier for the RAIF?
Although the RAIF was originally conceived for professional alternative investment managers, developments within private wealth suggest that it may also offer an attractive framework for certain family office structures.
Entrepreneurial families today frequently manage diversified portfolios spanning private equity, venture capital, real estate, infrastructure, private credit and direct operating businesses across multiple jurisdictions. In many respects, their investment activities increasingly resemble those of institutional investors.
As a consequence, governance has become an increasingly important consideration.
Institutional governance for entrepreneurial capital
As family wealth becomes more international and successive generations become involved in investment decision-making, many families seek governance structures capable of balancing entrepreneurial flexibility with professional oversight.
Within the appropriate regulatory framework, the RAIF may contribute to this institutionalisation by combining a flexible investment vehicle with the governance standards associated with an authorised AIFM and Luxembourg’s broader regulated fund ecosystem.
For families whose investment activities increasingly resemble those of professional investment platforms, this may provide an appropriate framework for long-term portfolio management.
Supporting increasingly sophisticated investment programmes
Family offices also increasingly participate in co-investments alongside institutional sponsors, establish dedicated investment platforms or pursue thematic investment strategies through specialist advisers.
The flexibility offered by the RAIF may facilitate these initiatives while providing a structure that is familiar to institutional counterparties and international service providers.
Equally, the availability of umbrella structures and multiple compartments may assist families wishing to segregate investment strategies, generations or categories of assets within a single legal framework.
Not a substitute for traditional holding structures
The RAIF should nevertheless be viewed as one tool within Luxembourg’s broader structuring toolbox rather than as a universal solution.
It remains reserved to well-informed investors and must be externally managed by an authorised AIFM. Accordingly, many entrepreneurial families will continue to find that a traditional holding structure or another Luxembourg vehicle better reflects their objectives.
Where, however, a family’s investment activities have reached a degree of sophistication comparable to those of institutional investment managers, the RAIF may provide an effective framework for combining long-term capital preservation, professional governance and operational flexibility.
This evolution illustrates a broader trend within the investment industry: the increasing convergence between institutional asset management and sophisticated private wealth.
VII. Beyond the anniversary: Why the RAIF continues to matter
Anniversaries naturally invite reflection on the past. The RAIF’s tenth anniversary, however, is perhaps more significant for what it says about the future of Luxembourg’s alternative investment funds industry than for what it reveals about its origins.
The RAIF has demonstrated that regulatory efficiency and investor protection are not mutually exclusive. By placing the authorised AIFM at the centre of the supervisory framework while preserving a robust governance ecosystem, Luxembourg anticipated a broader evolution in the alternative investment industry—one in which institutional investors increasingly assess the quality of investment managers, governance arrangements and operational infrastructure rather than relying exclusively on product-level supervision.
That philosophy remains highly relevant.
Private markets continue to evolve rapidly. Fund structures have become more sophisticated, fundraising models more diverse and investor expectations increasingly demanding. Sponsors now require investment vehicles capable of accommodating continuation funds, co-investment programmes, parallel structures, private credit strategies, infrastructure platforms and increasingly complex cross-border investments without sacrificing legal certainty or operational efficiency.
Against this backdrop, the RAIF has proved remarkably resilient.
Perhaps its greatest achievement is not that it has reduced the time required to establish an investment fund. Rather, it has demonstrated that a flexible legal framework can coexist with institutional governance standards, provided that the surrounding regulatory architecture is sufficiently robust.
The RAIF’s success has therefore become inseparable from Luxembourg’s broader investment funds ecosystem. The availability of experienced authorised AIFMs, depositaries, central administrators, auditors and specialised advisers enable sponsors to establish and operate sophisticated investment structures within a jurisdiction that has earned the confidence of institutional investors worldwide.
This combination of legislation, regulatory expertise and market infrastructure remains difficult to replicate.
For asset managers considering a European platform, for institutional investors allocating capital to private markets and for entrepreneurial families seeking to institutionalise the governance of long-term investment portfolios, the RAIF continues to offer a compelling structuring solution. Its enduring relevance stems not from any single feature but from its ability to evolve alongside the industry it was designed to serve.
Ten years after its introduction, the RAIF is no longer simply another Luxembourg investment vehicle. It has become one of the defining pillars of Luxembourg’s alternative investment funds framework and a reflection of the jurisdiction’s ability to adapt its legal environment to the evolving needs of global capital markets.
Choosing the right Luxembourg investment vehicle
While the RAIF has become one of Luxembourg’s most successful alternative investment fund regimes, it is not necessarily the appropriate solution for every project.
The choice of investment vehicle should always be assessed in light of the proposed investment strategy, the targeted investor base, the desired regulatory framework, tax considerations, governance objectives and the anticipated operational model. Depending on the circumstances, a SIF, a SICAR, a Part II fund, an unregulated partnership or another Luxembourg structure may provide a more appropriate solution.
To assist asset managers, institutional investors, family offices and their advisers in navigating Luxembourg’s investment fund landscape, Chevalier & Sciales has prepared a practical Comparison Table of Luxembourg Investment Vehicles. The guide provides a side-by-side overview of the principal Luxembourg fund structures, highlighting their regulatory framework, eligible investors, legal forms, tax regime and typical use cases.
Explore our comparison table of Luxembourg investment vehicles:
https://www.cs-avocats.lu/publications/comparison-table-of-luxembourg-investment-vehicles/
As with any structuring exercise, selecting the appropriate vehicle requires careful consideration of the specific objectives of the project. Obtaining legal advice at an early stage of the structuring process remains essential to ensure that the chosen framework aligns with the sponsor’s commercial objectives, investor expectations and applicable legal and regulatory requirements.
The RAIF demonstrated that regulatory efficiency and investor protection are not mutually exclusive.
Luxembourg RAIF (reserved alternative investment fund)
00 Set-up a RAIF in Luxembourg - summary of the main features
| RAIF | |
|---|---|
| English name/description | Reserved Alternative Investment Fund |
| Practical use | Alternative investment vehicle reserved to well-informed investors, used for the same range of alternative investment strategies as SIFs, including hedge funds, private equity, venture capital, real estate, infrastructure and private debt, and structured without prior CSSF product authorisation, with regulatory supervision exercised by the CSSF at the level of the authorised AIFM. |
| Applicable legislation | Law of 23 July 2016 (“RAIF Law”). |
| Authorisation and supervision by the CSSF | No. |
| Qualification as an AIF | Always an AIF. |
| Exemption from AIFMD full regime under lighter regime (AIFMD registration regime) | No. |
| External authorised AIFM requirement | Always required. |
| Eligible investors | Well-informed investors, namely institutional or professional investors (MiFID II), or other investors who confirm their status in writing and either invest at least EUR 100,000 or are assessed by a credit institution, investment firm, UCITS ManCo or authorised AIFM as having sufficient expertise, experience and knowledge. |
| Eligible assets | Unrestricted, unless the RAIF is established as a SICAR-type RAIF investing exclusively in risk capital. |
| Risk diversification requirements | Aligned with SIF risk diversification rules, unless the RAIF has opted to invest exclusively in risk capital and is therefore subject to the SICAR regime, as stated in its constitutive documents. |
| Legal form | • FCP • SICAV (SA, Sàrl, SCA, SCoSA, SCS, SCSp) • SICAF (SA, Sàrl, SCA, SCoSA, SCS, SCSp) The entities may be open-ended or closed-ended. |
| Umbrella structure | Yes. |
| Capital requirements | • FCP: EUR 1,250,000 to be reached within 24 months from the entry into force of the management regulations. • SICAV: EUR 1,250,000 to be reached within 24 months from the incorporation of the SICAV. |
| Required service providers | • Authorised AIFM. • Management company in case of an FCP • Depositary bank or professional of the financial sector providing depositary services, subject to conditions. • Administrative agent. • Registrar and Transfer Agent. • Approved statutory auditor. |
| Possibility of listing | Yes. |
| European passport | Yes (always under the full AIFMD regime). |
| Net asset value (NAV) calculation and redemption frequency | At least once a year. |
| Borrowings / leverage limits | No debt-to-equity ratio. |
| Overall income tax (corporate income tax and municipal business tax) | No income tax, unless investing only in risk capital, then SICAR tax regime applicable. |
| Subscription tax (NAV: net asset value) | • Rate: 0.01% of the NAV annually. • Exemptions apply. |
| Wealth tax | No wealth tax. |
| Withholding tax on dividends | Not subject to withholding tax. |
| Benefit from Double Tax Treaty network | • RAIFs investing in a portfolfio of risk capital (such as a SICAR) Access if set-up as a corporate entity (except if set-up under the form of a SCS/SCSp). • RAIFs not investing in a portfolio of risk capital (such as a SICAR), but set-up as: SICAV / SICAF: Limited to certain double tax treaties (see circular L.G. -A n°61 of the tax administration of 24 December 2024). FCP: see circular L.G.-A n°61 of the tax administration of 8 December 2024. |
| Benefit from the EU Parent Subsidiary Directive | No, unless RAIF that invests in a portfolio of risk capital (such as a SICAR). |
01 About this publication
This publication provides a comprehensive and up-to-date overview of the Luxembourg reserved alternative investment fund (RAIF) regime, covering its legal, regulatory, structuring and tax aspects, and taking into account recent legislative and regulatory developments relevant to RAIFs, and the EU cross-border distribution framework.
It is intended as a practical guide for asset managers, fund sponsors and institutional investors considering the establishment of a RAIF in Luxembourg. This publication is provided for general information purposes only and does not constitute any legal, tax, accounting or other professional advice under Luxembourg law or practice. No reliance should be placed on the information contained herein. Specific advice should be sought in relation to particular circumstances.
Directive (EU) 2024/927 amending Directive 2011/61/EU (“AIFMD II”) was adopted on 13 March 2024 and entered into force on 15 April 2024. Member States were required to transpose it by 16 April 2026 and to apply the transposing measures from 16 April 2026, with certain reporting-related measures applying from 16 April 2027. In Luxembourg, Bill of Law no. 8628 transposing AIFMD II was adopted by the Luxembourg Parliament and published in the Official Journal of the Grand Duchy of Luxembourg on 9 March 2026.
02 Introduction to the Luxembourg RAIF regime
The Luxembourg Reserved Alternative Investment Fund (fonds d’investissement alternatif réservé – “RAIF” or “FIAR”) is a dedicated alternative investment fund regime introduced by the law of 23 July 2016, as amended, most recently by the law of 21 July 2023 (the "RAIF Law"). The RAIF is designed for well-informed investors and was conceived to offer a fast and flexible onshore alternative to regulated Luxembourg fund vehicles, while operating fully within the European alternative investment fund regulatory framework.
Unlike specialised investment funds (SIFs) or risk capital investment companies (SICARs), a RAIF is not subject to direct product-level supervision by the Luxembourg financial regulator, the Commission de Surveillance du Secteur Financier (CSSF). Instead, regulatory oversight is exercised indirectly through the RAIF’s authorised alternative investment fund manager (AIFM). As a result, the RAIF offers a significantly faster time-to-market and enhanced operational flexibility, while remaining fully subject to the Alternative Investment Fund Managers Directive (AIFMD) through its authorised AIFM.
The RAIF regime has seen strong and sustained market adoption. According to the Luxembourg Trade and Companies Register, approximately 3,241 RAIFs were registered as at 15 January 2026, reflecting the regime’s widespread use among alternative asset managers.
A RAIF may pursue any investment strategy and invest in any type of asset, subject to the principle of risk spreading, unless it invests exclusively in risk capital.. RAIFs following a SIF-type investment policy are expected to comply with the same risk diversification principles applicable to specialised investment funds, as set out in CSSF Circular 25/901. RAIFs investing exclusively in risk capital may benefit from an exemption from diversification requirements and are instead subject to the SICAR regime, as reflected in the same circular.
A RAIF may be established in contractual form (fonds commun de placement – FCP) or as an open-ended or closed-ended corporate fund (SICAV or SICAF), and may adopt any corporate form available under Luxembourg law, including partnerships such as the société en commandite simple (SCS) or société en commandite spéciale (SCSp). RAIFs may be structured as umbrella funds with multiple compartments and share classes, allowing for segregated sub-fund structures without direct product-level regulation.
Access to a RAIF is reserved to well-informed investors, being institutional investors, professional investors or other investors meeting the applicable qualification criteria. There is no minimum investment requirement for institutional or professional investors, while a minimum investment of EUR 100,000 generally applies to other investors, unless they have been assessed by a credit institution, an investment firm, a UCITS management company or an authorised AIFM as having the appropriate expertise, experience and knowledge to adequately appraise the investment.
Each RAIF must be managed by a fully authorised alternative investment fund manager within the meaning of the AIFMD. Where the AIFM is established in a Member State of the European Economic Area, the RAIF may benefit from the pan-European marketing passport, allowing the marketing of its units or shares to professional investors across the European Union.
Recent EU cross-border distribution reforms have further enhanced this framework by harmonising rules on pre-marketing, marketing communications and the launch and discontinuation of marketing activities across the EU.
From a tax perspective, most RAIFs benefit from the same tax treatment as SIFs, being subject to an annual subscription tax (taxe d’abonnement) at a rate of 0.01% of their net assets, while remaining exempt from Luxembourg corporate income tax and withholding tax on distributions. RAIFs investing exclusively in risk capital may, subject to an election in their constitutive documents, opt for the tax regime applicable to SICARs.
03 What are the key features of the Luxembourg RAIF?
Fast and efficient time to market
The Luxembourg RAIF is not subject to product level supervision by the CSSF, enabling sponsors to launch funds more efficiently, while operating fully within the AIFMD framework.
Full authorised AIFM required
Each RAIF must appoint a fully authorised alternative investment fund manager (AIFM).
Designed for well-informed investors
Access is reserved for well-informed investors, being institutional investors, professional investors, or other investors meeting the applicable qualification criteria (including, where relevant, a minimum investment of EUR 100,000 or an appropriate professional assessment).
Broad structuring versatility
The RAIF can adopt any legal form available under Luxembourg law, may be established as an umbrella fund with multiple compartments and share classes, and can accommodate a wide range of alternative investment strategies, subject to applicable risk diversification rules.
Eligibility for the pan-European marketing passport for professional investors under the AIFMD
04 What changes does the RAIF legislation bring to Luxembourg fund structuring options?
In order to maintain the competitiveness of Luxembourg as a fund domicile and as a centre for fund servicing and distribution, the legislation of 12 July 2013 transposing the AIFMD into national law also incorporated measures aimed at modernising the country’s limited partnership regime. These measures included changes to the rules applicable to common limited partnerships and the introduction of a new type of vehicle without legal personality, the special limited partnership.
Both forms of limited partnership may be used for structuring regulated fund vehicles, such as SIFs and SICARs, as well as unregulated investment vehicles. Although common and special limited partnerships are not subject to direct product regulation, they are nevertheless subject to indirect supervision where they qualify as alternative investment funds and are therefore required to appoint an authorised alternative investment fund manager.
While unregulated limited partnerships have proved popular with fund promoters and investors, particularly for closed-ended vehicles investing in illiquid assets such as real estate and private equity, they are not suitable for all circumstances, in particular where investments in transferable securities or other liquid assets are envisaged. Moreover, although SCSs and SCSp’s are tax-transparent, there are situations in which a tax-opaque vehicle may be preferred, notably in order to benefit from Luxembourg’s network of double taxation treaties. In addition, unregulated limited partnerships cannot be structured as umbrella funds and are therefore unable to create segregated portfolios within legally distinct sub-funds.
The introduction of the RAIF regime was therefore intended to ensure the broadest possible range of structuring options for promoters, managers and investors, under a regime broadly similar to that applicable to SIFs, but without subjecting the fund itself to direct supervision by the CSSF. In doing so, the RAIF provides Luxembourg alternative investment funds with the possibility to avoid a double layer of supervisory requirements while retaining access to the AIFMD framework. AIFs subject to supervision at the level of their authorised AIFM thus have the choice between being established as regulated products (Part II funds, SIFs or SICARs) or as unregulated products (unregulated SCSs and SCSp’s or RAIFs).
05 How to set-up a Luxembourg RAIF?
Following the entry into force of the law of 21 July 2023, the formation formalities applicable to RAIFs have been streamlined. Where a RAIF is established by way of articles of association, there is no longer any requirement for a notary to formally acknowledge that the RAIF has been established and that an alternative investment fund manager (“AIFM”) has been appointed. The requirement for a notary to acknowledge the establishment of the RAIF and the appointment of its AIFM within five business days from its creation is maintained only for RAIFs formed under private deed, namely those established as an FCP, an SCS or an SCSp. RAIFs must be registered on the official list maintained by the Luxembourg Register of Commerce and Companies and made available on its website.
The constitutional documents of a RAIF depend on whether it is established in corporate or contractual form. They consist of articles of incorporation where the RAIF is incorporated as a public limited company (société anonyme or “SA”), a partnership limited by shares (société en commandite par actions or “SCA”) or a private limited liability company (société à responsabilité limitée or “Sàrl”); management regulations where the RAIF is established as a fonds commun de placement (“FCP”); or a limited partnership agreement where it is established as a common or special limited partnership (SCS or SCSp). Articles of incorporation must be executed in the form of a notarial deed, whereas management regulations and limited partnership agreements may be entered into under private deed.
Promoters of existing Luxembourg entities may also wish to convert such entities into RAIFs. In the case of regulated entities, this may be done in order to facilitate the rapid launching of new compartments, while unregulated limited partnerships may be converted in order to benefit from the possibility of adopting an umbrella structure.
An existing specialised investment fund (SIF), Part II fund or risk capital investment company (SICAR) may be converted into a RAIF in accordance with the applicable legislation and the provisions governing its constitutional documents, subject, where required, to the prior approval of the CSSF of the relevant amendments and to corresponding changes to the fund’s prospectus or issue document, unless the fund concerned is a SIF or SICAR that is not open to new investors. The conversion of an existing unregulated limited partnership requires an amendment to its limited partnership agreement, in accordance with the applicable contractual provisions.
The conversion of a non-Luxembourg entity into a RAIF is also possible, provided that the re-domiciliation of the entity is permitted under the laws of its jurisdiction of origin. Where re-domiciliation is not available, the conversion may alternatively be implemented by way of a contribution in kind, merger or another appropriate restructuring mechanism. In all cases, the entity must be brought into compliance with the AIFMD through the appointment of a fully authorised external AIFM by the time the conversion takes effect. The legislation further allows a fund established as a RAIF to be converted at a later stage into a regulated vehicle, such as a Part II fund, a SIF or a SICAR.
06 Who may manage a Luxembourg RAIF?
A RAIF is an undertaking for collective investment that automatically qualifies as an alternative investment fund (“AIF”) and, as such, cannot be structured as a non-AIF. This contrasts with certain specialised investment funds (“SIFs”) or risk capital investment companies (“SICARs”), which may fall outside the scope of the definition of an AIF under Luxembourg’s law of 12 July 2013 on alternative investment fund managers where, for example, they do not raise capital from a number of investors, have a single investor, or where access is restricted to a predefined group of investors.
With very limited exceptions (as described below), a RAIF must appoint an external alternative investment fund manager (“AIFM”) that is fully authorised under the AIFMD, whether established in Luxembourg or in another EU Member State, and which does not benefit from the sub-threshold registration regime under the AIFMD. That regime applies to managers with assets under management below EUR 100 million, or EUR 500 million in the case of unleveraged funds with a lock-up period of at least five years. As a result, internally managed AIFs and funds managed by AIFMs benefiting from an exemption from full authorisation under the AIFMD, including under the de minimis thresholds, are not eligible to qualify as RAIFs.
In this context, AIFMD II further emphasises the requirement for authorised AIFMs to maintain adequate substance and effective oversight of delegated functions, with the aim of preventing the creation of so-called “letter-box” entities. These developments do not affect the obligation for a RAIF to be managed by a fully authorised AIFM, but they reinforce the importance of robust governance and delegation arrangements at AIFM level. In accordance with Article 2.3(c) and (d) of the AIFMD, the legislation nevertheless provides for limited exemptions from the obligation to appoint an external AIFM in respect of RAIFs that act in the public interest and are managed by supranational or international institutions, such as the European Central Bank, the European Investment Bank or the European Investment Fund, European development finance institutions, bilateral development banks, the World Bank or the International Monetary Fund, as well as RAIFs managed by a national central bank.
Although a RAIF is not itself subject to direct authorisation or ongoing supervision by the CSSF, it is indirectly regulated through the requirements applicable to its appointed AIFM, which must ensure that the RAIF complies with the provisions of the AIFMD. The AIFM must notify its home supervisory authority, whether in Luxembourg or in another EU Member State, of its appointment as manager of a RAIF. A non-EU AIFM may be permitted to manage a RAIF in the future, provided that it is fully authorised in its home jurisdiction and that the AIFMD third-country passport becomes available.
If the appointed external AIFM ceases to manage the RAIF, whether at its own initiative or at the initiative of the fund, a replacement authorised external AIFM must be appointed within a maximum period of two months. Failing such appointment, the directors, managers or management company of the RAIF must, within one month following the expiry of that period, apply to the competent District Court (tribunal d’arrondissement) in Luxembourg for the RAIF to be placed into liquidation.
07 What documentations and reporting requirements must a Luxembourg RAIF comply with?
A RAIF must draw up an issue document, prospectus or placement memorandum containing all information necessary for investors to be able to make an informed judgement about the proposed investment and the risks associated therewith. A RAIF’s issue document will typically include the disclosure requirements mandated by the AIFMD, which are designed to provide investors with the information required to make such an informed judgement. The legislative materials accompanying the RAIF Law expressly allow these disclosure requirements to be satisfied by other means, provided that the relevant information is made available to investors. The issue document must be kept up to date in all material respects where additional securities are issued to new investors.
The issue document must state prominently on its cover page that the RAIF is not subject to supervision by any Luxembourg supervisory authority. Subject to this requirement, the RAIF Law offers broad flexibility as regards the content of a RAIF’s constitutional and issue documents. In practice, and in order to avoid the need to amend constitutional documents each time a new compartment is launched, such documents are typically drafted in a generic manner, with the specific features of each sub-fund described in a dedicated issue document. In such case, each sub-fund’s issue document must clearly indicate that the RAIF is structured as an umbrella fund, in a manner comparable to the practice applicable to Luxembourg-domiciled SIFs and SICARs.
RAIFs are required to prepare and publish audited annual reports within six months following the end of their financial year. Such annual reports must be reviewed by a Luxembourg-approved statutory auditor and must contain at least the minimum information required by Appendix I of the RAIF Law and Article 22 of the AIFMD. Umbrella RAIFs may prepare separate annual reports for each sub-fund, provided that, in addition to the financial information relating to the relevant compartment, the report also includes consolidated financial information covering the other sub-funds of the RAIF, in line with a practice accepted by the CSSF for umbrella SIFs and SICARs.
08 What regulatory oversight is a RAIF subject to?
RAIFs are not subject to direct authorisation, supervision or ongoing oversight by the Commission de Surveillance du Secteur Financier (“CSSF”) and may therefore be launched without obtaining regulatory approval either prior to or following their establishment. They are, however, indirectly subject to the requirements of the Alternative Investment Fund Managers Directive (“AIFMD”) through their appointed authorised alternative investment fund manager (“AIFM”).
Recent legislative developments, including the adoption of Directive (EU) 2024/927 amending the AIFMD (“AIFMD II”), further reinforce the central role of the authorised AIFM in the governance, risk management and regulatory oversight of alternative investment funds, including RAIFs. While AIFMD II does not alter the core characteristics of the RAIF regime as an unregulated product at fund level, it strengthens supervisory expectations in relation to AIFM substance, delegation arrangements, liquidity risk management tools and regulatory reporting, which are expected to have an indirect impact on RAIF structures through their authorised AIFM.
In particular, the AIFM must hold the appropriate authorisation to manage funds pursuing the relevant investment strategy, as certain AIFMD authorisations in Luxembourg are limited to specific strategies. For the purposes of anti-money laundering and counter-terrorist financing (“AML/CFT”) matters, the competent authority for RAIFs is the Luxembourg registration duties, estate and VAT authority (Administration de l’enregistrement, des domaines et de la TVA – “AED”).
Where the AIFM is established outside Luxembourg, it must have obtained authorisation to provide management services in Luxembourg under Article 33 of the AIFMD relating to the passporting of management services. In such case, the RAIF’s constitutional and issue documents must be filed with the CSSF. Where a RAIF is managed by a Luxembourg-authorised AIFM, there is no systematic review of the fund’s documentation by the regulator. However, the CSSF may refuse the passporting of management services where the documentation submitted by a foreign AIFM does not demonstrate that its authorisation covers the management of the relevant type of AIF.
Once a RAIF has been established, no regulatory approval is required for subsequent actions during the life of the fund, including amendments to its documentation, the launch of new sub-funds or compartments, changes of service providers or the liquidation of the RAIF.
09 What investments may a RAIF undertake?
As a matter of principle, a Luxembourg reserved alternative investment fund (RAIF) may pursue any investment strategy and invest in any type of asset, without restriction as to asset class, geography or technique, provided that its portfolio is managed in accordance with the principle of risk spreading.
An exception applies where the RAIF invests exclusively in risk capital and has elected to be subject to the tax regime applicable to investment companies in risk capital (SICARs). In that case, the RAIF is exempt from diversification requirements. For these purposes, “risk capital” is understood, by reference to the SICAR regime, as the direct or indirect contribution of assets to entities in the expectation of their launch, development or listing on a stock exchange.
Risk diversification framework
The determination of the appropriate level of risk spreading lies with the RAIF’s governing body, which is responsible for ensuring that the investment policy is implemented in compliance with the RAIF Law and applicable market practice. While the RAIF Law itself does not prescribe quantitative diversification limits, the parliamentary works indicate that the diversification principles applicable to specialised investment funds (SIFs) should be taken into account.
In this context, CSSF Circular 07/309 has been superseded by CSSF Circular 25/901, which sets out the relevant risk diversification principles for SIFs and, by extension, for RAIFs of the SIF-type. Accordingly, RAIFs that are subject to risk-spreading requirements are expected to comply with the principles set out in Circular 25/901.
For RAIFs (and their compartments) reserved to well-informed or professional investors, this generally implies that:
- as a rule, no more than 50% of the assets of a RAIF or compartment may be invested in a single issuer, entity or asset; and
- a higher concentration limit of up to 70% may be permitted in the case of a single infrastructure investment.
These limits are applied on a compartment-by-compartment basis and are subject to appropriately disclosed ramp-up and, where relevant, wind-down periods, in line with Circular 25/901.
Liquidity considerations and AIFMD II
From a regulatory perspective, investment flexibility at fund level is complemented by requirements applicable at the level of the authorised alternative investment fund manager (AIFM). In particular, AIFMD II introduces a harmonised framework for liquidity management tools, aimed primarily at funds investing in less liquid assets. While such tools are implemented and activated by the authorised AIFM rather than the RAIF itself, they may be reflected in the liquidity management arrangements of a RAIF depending on its investment strategy and liquidity profile.
Investments in specific asset classes (including virtual assets)
Within this broadly permissive framework, certain asset classes are subject to additional regulatory expectations. By way of example, the CSSF has provided guidance on investments in virtual assets in its FAQ on Virtual Assets (UCIs). The CSSF has clarified that an AIF managed by an authorised AIFM may invest directly or indirectly in virtual assets, provided that:
- the fund’s interests are marketed exclusively to professional investors; and
- the AIFM has obtained an extension of its authorisation to cover the relevant investment strategy.
The CSSF has further clarified, inter alia, that a Luxembourg depositary may act as depositary for funds investing directly in virtual assets subject to certain conditions, and that appropriate AML/CFT risk assessments and due diligence must be carried out in respect of such assets.
10 Which legal forms may a Luxembourg RAIF adopt?
A RAIF may be structured as a common contractual fund (fonds commun de placement or “FCP”), which does not have legal personality, as an open-ended investment company (société d’investissement à capital variable or “SICAV”), or as a closed-ended investment company (société d’investissement à capital fixe or “SICAF”).
A RAIF established in the form of an FCP must appoint a Luxembourg management company. Such management company may also act as the RAIF’s alternative investment fund manager (“AIFM”) where it is duly authorised as such by the CSSF; otherwise, the FCP must appoint a separate AIFM authorised in Luxembourg or in another EU Member State.
A RAIF established in the form of a SICAV or a SICAF may be constituted under any corporate form permitted by Luxembourg law, including a public limited company (société anonyme or “SA”), a private limited liability company (société à responsabilité limitée or “Sàrl”), a corporate partnership limited by shares (société en commandite par actions or “SCA”), a common or special limited partnership (SCS or SCSp), or a co-operative company organised as a public limited company (société coopérative sous forme de société anonyme or “SCoSA”).
11 Can Luxembourg RAIFs have multiple compartments and share classes?
A RAIF may be structured as an umbrella fund with one or more compartments or sub-funds, with the assets and liabilities of each sub-fund legally segregated from those of the other sub-funds, unless otherwise provided for in the constitutional documents of the RAIF. Cross-investment between sub-funds is permitted, subject to the same conditions as those applicable to SIFs. The liquidation of a sub-fund does not result in the liquidation of the other sub-funds or of the RAIF as a whole, provided that at least one other sub-fund remains in existence.
Where provided for in the RAIF’s issue document, each sub-fund may have its own distinct investment policy, and the rules governing the issue and redemption of securities or ownership interests may be tailored to each specific sub-fund. A single umbrella structure may combine open-ended and closed-ended sub-funds, fully funded sub-funds and compartments operating on a drawdown basis, and, in the case of limited partnerships, sub-funds issuing partnership interests either in the form of securities or through partnership capital accounts.
Each sub-fund may appoint its own investment manager or investment adviser, as well as its own investment committee or advisory board. The RAIF must, however, have a single managing body, such as the board of directors in the case of a fund established as an SA, the general partner in the case of a limited partnership, or the management company in the case of an FCP, and a single depositary, central administrator, external auditor and AIFM at the level of the RAIF.
In addition, a RAIF or any of its sub-funds may issue multiple classes of securities subject to different fee structures, distribution or carried interest arrangements, or currency hedging policies, and which may be denominated in different currencies. Sub-funds may also be reserved for one or more investors or for specific categories of investors.
12 What corporate rules apply to a Luxembourg RAIF?
SICAV-RAIFs established as an SA, SCA or Sàrl benefit from corporate rules that are more flexible than those applicable to commercial companies or other types of corporate structures governed by the Luxembourg law of 10 August 1915 on commercial companies. In particular, there are no statutory constraints on the rules governing the issue and redemption of shares, including the determination of the issue price, which must be set out in the articles of association, subject to the requirement that at least 5% of each share be paid up upon issue.
Corporate RAIFs are subject to a minimum capital requirement of EUR 1.25 million, which must be reached within 24 months of their incorporation and may consist of subscribed capital and share premium. They are not required to create a statutory reserve. The payment of interim or annual dividends is subject only to compliance with the applicable minimum capital requirements.
RAIFs established as FCPs are not subject to statutory constraints on the issue and redemption of units, including rules applicable to the issue price, which must be set out in the management regulations. As with corporate RAIFs, the payment of distributions is subject only to the applicable minimum capital requirements.
SICAV-RAIFs established in the form of limited partnerships benefit from additional structuring flexibility. They may issue partnership interests either in the form of securities or through partners’ capital accounts (comptes d’associés), and they enjoy broad contractual freedom to determine, in the limited partnership agreement, voting rights, entitlements to profits and losses and to distributions, as well as the rules governing the transfer of partnership interests.
13 What are a Luxembourg RAIF’s servicing requirements?
A RAIF must entrust the safekeeping of its assets to a Luxembourg depositary, being either a Luxembourg-established credit institution or the Luxembourg branch of a credit institution established in another EU Member State. Where a RAIF invests mainly in non-financial instruments and is subject to a lock-up period of at least five years following its initial investment, it may alternatively appoint a licensed professional depositary that is not a credit institution.
As a collective investment scheme, the central administration of a RAIF must be carried out in Luxembourg. Administrative and transfer agency functions must be performed by an administrator and registrar authorised by the CSSF. RAIFs are required to appoint an authorised AIFM, a depositary subject to the AIFMD liability regime, and an external auditor with appropriate qualifications and experience, approved by the CSSF as auditor of a Luxembourg UCITS, Part II fund, SIF or SICAR.
While the administrative functions may, in theory, be carried out by the RAIF itself or by its AIFM, where established in Luxembourg, in practice a specialised Luxembourg fund administrator is generally appointed, either by the AIFM in accordance with the AIFMD delegation rules or directly by the RAIF’s managing body.
The AIFM may appoint one or more investment managers or investment advisers to manage the assets of the RAIF or of its sub-funds, subject to Article 20 of the AIFMD and Article 78 of Commission Delegated Regulation (EU) No 231/2013 of 19 December 2012. A non-regulated entity may only be appointed as investment manager or sub-investment manager of a RAIF subject to the prior approval of the AIFM’s competent supervisory authority.
As a collective investment scheme, the administration of the RAIF must be carried out in Luxembourg, and fund administration and transfer agency must be carried out by an administrator and registrar authorised by the CSSF. RAIFs must appoint an authorised AIFM, a depositary subject to the AIFMD liability regime, and an external auditor, which must have appropriate qualifications and experience and be approved by the CSSF as auditor of a Luxembourg UCITS, Part II fund, SIF or SICAR.
While administration may in theory be carried out by the RAIF itself or its AIFM, if established in Luxembourg, as a rule a specialised Luxembourg fund administrator will be appointed, either by the AIFM, subject to AIFMD delegation rules, or directly by the RAIF’s management body.
The AIFM may appoint one or more investment managers or advisers to manage the assets of the RAIF or of its sub-funds, subject to article 20 of the AIFMD and article 78 of the European Commission’s Level 2 regulation of December 2012. A non-regulated entity may only be appointed as an investment manager or as sub-investment manager of a RAIF subject to prior approval by the AIFM’s regulator.
14 Who may invest in a Luxembourg RAIF?
A RAIF may accept investments only from qualified or “well-informed” investors, as defined in the SIF and SICAR legislation. These comprise institutional investors (as defined by the CSSF in accordance with established practice), professional investors, and other investors who do not qualify as either institutional or professional investors, but who invest or commit at least EUR 100,000 in the RAIF and confirm in writing that they adhere to the status of well-informed investor.
Investments of less than EUR 100,000 may be accepted from such investors, provided that they have been assessed and certified by a credit institution, an investment firm, an authorised AIFM or a management company as having the expertise, experience and knowledge necessary to adequately understand and assess an investment in the RAIF. In addition, directors, officers and other persons involved in the management of the RAIF are permitted to invest in the RAIF, even if they do not fall within any of the above investor categories.
By complying with the AIFMD notification process for passporting, a RAIF may be marketed to professional investors in other EU Member States, as it is an EU-domiciled alternative investment fund managed by an authorised AIFM. A RAIF’s offering document must contain all information necessary to enable investors to assess an investment in the RAIF. As noted above, the cover page of the RAIF’s offering document must clearly state that the RAIF is not subject to supervision by the CSSF, unlike SIFs or SICARs. The offering document must be kept up to date and amended prior to the acceptance of new investors. Sub-funds may have separate offering documents, provided that they clearly indicate that the RAIF is structured as an umbrella fund with multiple sub-funds.
15 What taxation applies to a Luxembourg RAIF?
The Luxembourg RAIF framework provides for two alternative tax treatments at fund level. As a default position, a RAIF is subject to a tax regime broadly aligned with that applicable to specialised investment funds (SIFs). By way of derogation, a RAIF whose constitutive documents restrict its investment policy to assets qualifying as risk capital may elect to be subject to a tax regime comparable to that applicable to Luxembourg investment companies in risk capital (SICARs). Where a RAIF is structured as an umbrella fund, this tax election must be applied consistently across all compartments and cannot vary from one sub-fund to another.
General tax regime (Default regime, SIF-type RAIFs)
In principle, a Luxembourg reserved alternative investment fund (RAIF) is subject to the same default tax regime as a specialised investment fund (SIF), unless it validly elects the risk capital (SICAR-like) regime where available. RAIFs structured as contractual funds (fonds commun de placement) or as common or special limited partnerships (SCS/SCSp) are, as a rule, treated as tax transparent for Luxembourg direct tax purposes and are therefore not subject to Luxembourg corporate income tax at fund level, save where specific rules (including the reverse hybrid rules implementing ATAD 2) may lead to taxation at the level of the vehicle in certain circumstances.
Under this general regime, RAIFs are, as a matter of Luxembourg domestic tax law, exempt from Luxembourg corporate income tax, municipal business tax and net wealth tax. Instead, RAIFs are subject to an annual subscription tax (taxe d’abonnement) at a rate of 0.01% of their net assets. The subscription tax is assessed on the basis of the net asset value of the RAIF calculated at the end of each calendar quarter and is payable on a quarterly basis.
The RAIF Law provides for a number of exemptions from the subscription tax. In particular, no subscription tax is levied on assets invested in other Luxembourg collective investment undertakings that are themselves subject to subscription tax. Exemptions may also apply, subject to statutory conditions, to RAIFs investing in certain money market instruments, bank deposits or microfinance, as well as to RAIFs whose investors consist exclusively of pension funds or comparable institutions. Compartments or share classes reserved to pension schemes may likewise benefit from such exemptions.
Optional tax regime for RAIFs investing in risk capital (SICAR-type RAIFs)
A Luxembourg reserved alternative investment fund (RAIF) may elect an alternative tax regime where its constitutive documents expressly provide that its exclusive investment objective consists of investments qualifying as risk capital and where the relevant provisions of the RAIF Law are applied. This option is available to RAIFs established in corporate form (excluding RAIFs structured as fonds commun de placement).
This alternative regime is designed to mirror, in substance, the tax treatment applicable to Luxembourg investment companies in risk capital (SICARs). Although the RAIF Law does not itself define the concept of risk capital, the parliamentary preparatory works indicate that reference should be made to the principles developed under the SICAR regime, as reflected in CSSF Circular 06/241 of 5 April 2006, which has been repealed and replaced by CSSF Circular 25/901.
RAIFs applying the risk capital regime are, in principle, subject to Luxembourg corporate income tax and municipal business tax and may, subject to applicable conditions and anti-abuse rules, be regarded as Luxembourg tax residents for domestic law and treaty purposes. However, income and capital gains derived from assets qualifying as risk capital are excluded from the taxable base. Income arising from assets held temporarily pending their investment into qualifying risk capital may also benefit from this exemption, provided that such assets are effectively invested into risk capital within a period of twelve months.
By contrast with the general SIF-type regime, no subscription tax (taxe d’abonnement) is levied on RAIFs applying the risk capital regime. Income that does not qualify as risk capital income remains subject to Luxembourg taxation in accordance with ordinary tax principles, and expenses or losses directly connected with exempt income are not deductible from the taxable base.
RAIFs subject to the risk capital regime are exempt from Luxembourg net wealth tax, subject to the minimum net wealth tax applicable to fully taxable Luxembourg companies. As from 1 January 2025, this minimum net wealth tax is determined solely by reference to the total balance sheet size and currently amounts to EUR 535, EUR 1,605 or EUR 4,815 per year, depending on the applicable balance sheet threshold.
Where a RAIF applying the risk capital regime is established as a common or special limited partnership (SCS or SCSp), it is treated as tax transparent for Luxembourg direct tax purposes. As a result, no Luxembourg corporate income tax or municipal business tax is levied at fund level, irrespective of the application of the risk capital regime, and taxation is determined at the level of the investors.
Taxation of investors in a RAIF
Distributions made by a RAIF to its investors, as well as proceeds realised upon the redemption or repurchase of RAIF units or shares, are not subject to Luxembourg withholding tax.
Non-Luxembourg-resident investors in a RAIF who do not act through a Luxembourg permanent establishment are, as a rule, not subject to Luxembourg taxation on income or capital gains derived from their investment in the RAIF.
VAT
Management services supplied to a RAIF may benefit from the Luxembourg VAT exemption applicable to the management of investment funds, subject to the conditions laid down in Luxembourg VAT legislation and relevant case law.
Other services provided to a RAIF, including purely technical services, ancillary or certain supervisory and control services, may fall outside the scope of the VAT exemption, depending on their nature and the circumstances in which they are supplied.
International tax considerations
RAIFs subject to the general tax regime and established in corporate form may, subject to the applicable conditions, benefit from certain double taxation treaties concluded by Luxembourg.
RAIFs applying the risk capital regime and established as tax-opaque entities are generally regarded as Luxembourg tax residents for domestic law and treaty purposes. By contrast, RAIFs established as contractual funds or limited partnerships are typically treated as tax transparent for Luxembourg tax purposes, which may allow investors, subject to the applicable treaty provisions, to claim treaty benefits directly.
16 What is the practical use of a Luxembourg RAIF?
The practical use of a RAIF is that it serves as an alternative investment vehicle reserved to well-informed investors, used for the same broad range of alternative investment strategies as SIFs, including hedge funds, private equity, venture capital, real estate, infrastructure, private debt and similar asset classes. It is particularly attractive in practice because it can be structured without prior CSSF product authorisation, while regulatory supervision is exercised indirectly through the authorised AIFM, which remains subject to CSSF oversight.
17 How can we assist you?
Drawing on longstanding experience advising on Luxembourg alternative investment funds and RAIF structures, our investment management team advises asset managers, sponsors and institutional investors on the structuring, establishment and ongoing operation of Luxembourg investment funds. We support our clients throughout the entire lifecycle of their funds, including in particular by:
- Advising on the selection and structuring of the most appropriate investment vehicle, taking into account marketing considerations, regulatory requirements, legal structuring objectives and tax efficiency
- Assisting with the establishment of RAIFs and other Luxembourg fund vehicles, including the preparation and negotiation of offering documents (PPMs), constitutional documents and, where relevant, the incorporation of the fund and its general partner
- Assisting with the appointment and coordination of key service providers, including depositary banks, authorised AIFMs, central administrators, registrars and transfer agents, and auditors
- Advising on the migration, restructuring or re-domiciliation of offshore or non-Luxembourg funds into Luxembourg, including conversions into RAIFs
- Providing ongoing corporate, regulatory and fund governance support throughout the life of the fund, including amendments to fund documentation, restructurings, changes to fund terms and the launch or liquidation of compartments or share classes
- Assisting with changes of service providers, including depositary banks, administrators, auditors or registrars and transfer agents
- Advising on fund distribution matters, including AIFMD passporting, local private placement regimes and, where relevant, the listing of fund interests on the Luxembourg Stock Exchange (regulated market or Euro MTF)
- Supporting cross-border registrations and marketing initiatives in other jurisdictions, in coordination with local counsel
- Advising on AIFMD, AIFMD II and related regulatory developments, including their impact on AIFM substance, delegation arrangements and ongoing compliance.
- Keeping clients informed of legal and regulatory developments affecting Luxembourg investment funds and the alternative asset management industry
Compare two vehicles:
| SIF | SICAR | RAIF | SPF | Unregulated SCS/SCSp | Ordinary Luxembourg company | |
|---|---|---|---|---|---|---|
| Applicable legislation | Law of 13 February 2007 (“SIF Law”). | Law of 15 June 2004 (“SICAR Law”). | Law of 23 July 2016 (“RAIF Law”). | Law of 11 May 2007 (“SPF Law”). | Law of 10 August 1915 (“Company Law”). | Law of 10 August 1915 (“Company Law”). |
| Authorisation and supervision by the CSSF | Yes. | Yes. | No. | No. | No. | No. |
| Qualification as an AIF | Yes, unless exempt. It is exempt in case of existence of pre-existing group (i.e. family members). | Yes, unless exempt. It is exempt in case of existence of pre-existing group (i.e. family members). | Always an AIF. | In principle, no (as it would not be considered as “raising” capital from a number of investors as the structure generally serves for the investment of the private wealth of a “pre-existing group” (as defined in the Esma guidelines on key concepts of the AIFMD)). | Non-AIF, unless activities fall within the scope of article 1 (39) of the AIFM Law. | Non-AIF, unless activities fall within the scope of article 1 (39) of the AIFM Law. |
| Exemption from AIFMD full regime under lighter regime (AIFMD registration regime) | Possible. | Possible. | No. | Not applicable. | Possible. | Possible. |
| External authorised AIFM requirement | Required in case the entity is an AIF that is not self-managed and above the AIFMD threshold. | Required in case the entity is an AIF that is not self-managed and above the AIFMD threshold. | Always required. | Not applicable. | Required in case the entity is an AIF that is not self-managed and above the AIFMD threshold. | Required in case the entity is an AIF that is not self-managed and above the AIFMD threshold. |
| Eligible investors | Well-informed investors, namely institutional or professional investors (MiFID II), or other investors who confirm their status in writing and either invest at least EUR 100,000 or are assessed by a credit institution, investment firm, UCITS ManCo or authorised AIFM as having sufficient expertise, experience and knowledge. | Well-informed investors, namely institutional or professional investors (MiFID II), or other investors who confirm their status in writing and either invest at least EUR 100,000 or are assessed by a credit institution, investment firm, UCITS ManCo or authorised AIFM as having sufficient expertise, experience and knowledge. | Well-informed investors, namely institutional or professional investors (MiFID II), or other investors who confirm their status in writing and either invest at least EUR 100,000 or are assessed by a credit institution, investment firm, UCITS ManCo or authorised AIFM as having sufficient expertise, experience and knowledge. | Restricted to: • natural persons acting in the context of the management of their personal wealth; • management entities acting solely in the interest of the private wealth (e.g. trusts, private foundations); and intermediaries acting for the account of the above mentioned eligible investors (e.g. bank acting under a fiduciary agreement). | Unrestricted. | Unrestricted. |
| Eligible assets | Unrestricted. The investment objective and strategy of the fund is subject to the prior approval of the CSSF. | Restricted to investments in securities representing risk capital as specified in CSSF Circular 25/901 which has replaced Circular 06/241. The circular clarifies the criteria applied by the CSSF when assessing whether investments pursued by a SICAR qualify as risk capital, notably the intention to develop the target entity, the existence of a specific risk going beyond mere market risk, an exit strategy and, where appropriate, a degree of control or supervision A SICAR may use derivatives for hedging purposes or if such transactions are necessary to the realisation of its investment policy. However, investments in derivatives may not be the object of its investment policy, as they are not used, in principle, to create value in itself or to contribute to the development of the target entity. The investment of a SICAR in real estate is only possible through intermediary vehicles (such as SPVs) or real-estate funds. The underlying real-estate assets must meet the criteria of risk capital set out in CSSF circular 25/901. | Unrestricted, unless the RAIF is established as a SICAR-type RAIF investing exclusively in risk capital. | Restricted to acquisition, detention, management and realisation of financial assets. The SPF is not allowed to carry out commercial activities or to hold directly real estate (except for its own use or through its participations). | Unrestricted. | Unrestricted. |
| Risk diversification requirements | Risk diversification requirements are set out in CSSF Circular 25/901. For SIFs and compartments thereof reserved for well-informed or professional investors, the following concentration limits apply - a maximum of 50% of assets may be invested in a single issuer, entity, or asset; - a higher limit of up to 70% applies to a single infrastructure investment. The circular also allows a defined ramp-up period and a wind down period up to 4 years for private investments, during which limits may not apply as described in the sales document. | No risk diversification requirements. A SICAR may set investment limits in its sales document and may include ramp up and wind down periods during which those self-imposed limits do not apply. | Aligned with SIF risk diversification rules, unless the RAIF has opted to invest exclusively in risk capital and is therefore subject to the SICAR regime, as stated in its constitutive documents.. | No risk diversification requirements. | No risk diversification requirements. | No risk diversification requirements. |
| Legal Form | • FCP • SICAV (SA, Sàrl, SCA, SCoSA, SCS, SCSp) • SICAF (SA, Sàrl, SCA, SCoSA, SCS, SCSp) The entities may be open-ended or closed-ended. | • SA • Sàrl • SCA • SCS • SCSp • SCoSA The entities may be open-ended or closed-ended. | • FCP • SICAV (SA, Sàrl, SCA, SCoSA, SCS, SCSp) • SICAF (SA, Sàrl, SCA, SCoSA, SCS, SCSp) The entities may be open-ended or closed-ended. | • SA • Sàrl • SCA • SCSA | • SCS • SCSp | • SA, Sàrl, SCA • SAS • SCoSA • SCS • SCSp |
| Umbrella structure | Yes. | Yes. | Yes. | No. | No. | No. |
| Capital requirements | EUR 1,250,000 to be reached no later than 24 months following the authorisation by the CSSF. | EUR 1,000,000 to be reached no later than 24 months following the auhorisation by the CSSF. | • FCP: EUR 1,250,000 to be reached within 24 months from the entry into force of the management regulations. • SICAV: EUR 1,250,000 to be reached within 24 months from the incorporation of the SICAV. | Depends on the form: • SA / SCA: EUR 30,000 • Sàrl: EUR 12,000 • SCSA: no minimum capital. | No minimum capital requirement. | Depends on the form: • SA / SCA: EUR 30,000 • Sàrl: EUR 12,000 No minimum capital requirement for other legal forms. |
| Required service providers | • In case of an AIF, registered AIFM or authorised AIFM in case of an AIF above threshold. • Management company in case of an FCP. • Depositary bank or professional of the financial sector providing depositary services, subject to conditions. • Administrative agent. • Registrar and Transfer Agent. • Approved statutory auditor. | • In case of an AIF, registered AIFM or authorised AIFM in case of AIF above threshold. • Depositary bank or professional of the financial sector providing depositary services, subject to conditions. • Administrative agent. • Registrar and Transfer Agent. • Approved statutory auditor. | • Authorised AIFM. • Management company in case of an FCP • Depositary bank or professional of the financial sector providing depositary services, subject to conditions. • Administrative agent. • Registrar and Transfer Agent. • Approved statutory auditor. | Registered auditor in principle not required unless two of the following criteria are met: (i) net turnover above EUR 8.8 million, (ii) balance sheet above EUR 4.4 million and (iii) average number of employees above 50. However, depending on the legal form of the company, there may be an obligation to appoint a commissaire aux comptes. | For SCS: • Alternative Investment Fund Manager (if the SCS qualifies as an AIF). • No requirement to appoint a depositary (except if the SCS qualifies as an AIF and is managed by a duly authorised AIFM). For SCSp: • Alternative Investment Fund Manager (if the SCSp qualifies as an AIF). • No requirement to appoint a depositary (except if the SCSp qualifies as an AIF and is managed by a duly authorised AIFM). | Registered auditor in principle not required unless the company is an AIF managed by an AIFM with AUM above the threshold or two of the following criteria are met: (i) net turnover above EUR 8.8 million, (ii) balance sheet above EUR 4.4 million and (iii) average number of employees above 50. However, depending on the legal form of the company, there may be an obligation to appoint a commissaire aux comptes. On 28 July 2023, draft bill 8286 (the Draft Bill) was released, aiming to overhaul Luxembourg accounting law applicable to undertakings (the New Law). |
| Possibility of listing | Yes. | Yes, but difficult in practice. | Yes. | No. | In principle, no. The SCS/SCSp may however issue debt securities that are eligible to be listed on the stock exchange. | Yes. |
| European passport | Yes, but needs to fall under the scope of the full AIFMD regime. | Yes, but needs to fall under the scope of the full AIFMD regime. | Yes (always under the full AIFMD regime). | No. | No, unless it falls under the scope of the full AIFMD regime. | No, unless it falls under the scope of the full AIFMD regime. |
| Net asset value (NAV) calculation and redemption frequency | At least once a year. | The valuation of the assets of the company is based on the "fair value". | At least once a year. | Not required. | Not required. | Not required. |
| Borrowing / leverage limits | No debt-to-equity ratio. According to circular 25/901, SIFs may borrow cash for investment and operational purposes. The SIF or compartment may set its own borrowing limits. | No debt-to-equity ratio.No debt-to-equity ratio. CSSF Circular 25/901, limits the use of borrowing in consideration to the specific objective of the SICAR. Reference should be made to the general principles laid down in Chapter 5 of the circular. When borrowing cash, the fund or the compartment may encumber assets. | No debt-to-equity ratio. | Tax of 0.25% on the debt that exceeds 8 times the paid-up capital increased by the issue premium. | No debt-to-equity ratio. | No provision in Luxembourg law. However, there is a specific administrative practice. |
| Overall income tax (corporate income tax and municipal business tax) | No income tax. | • General aggregate rate: 23.87%. In certain cases, reduced corporate income tax rates may apply. Income derived from transferable securities (e.g. dividends received and capital gains realised on the sale of shares) is exempt. Income on cash held for the purpose of a future investment is also exempt (for one year). | No income tax, unless investing only in risk capital, then SICAR tax regime applicable. | No income tax. | No corporate income tax applicable. Municipal business tax of 6.75% applicable in very limited circumstances, namely in case the SCS/SCSp (i) carries out a commercial activity or (ii) is deemed to carry out a commercial activity. A SCS/SCSp is deemed to carry out a commercial activity if its general partner is a Luxembourg public or private limited liability company holding at least 5% of the partnership interests. With a proper structuring of the GPs partnership interest it should be possible to avoid the deemed commercial characterisation of the SCS/SCSp. | General aggregate rate: 23.87%, but 100% exemption for dividends, liquidation proceeds and capital gains from qualifying participations. |
| Subscription tax (NAV: net asset value) | • Rate: 0.01% of the NAV annually. • Tax exemptions: certain money market and pension funds or SIFs investing in other funds which are already subject to subscription tax. | No subscription tax. | • Rate: 0.01% of the NAV annually. • Exemptions apply. | Annual subscription tax of 0.25% on the amount of paid up capital and issue premium (if any). | No subscription tax. | No subscription tax. |
| Wealth tax | No wealth tax. | No wealth tax. | No wealth tax. | No wealth tax. | No wealth tax. | 0.5% on a taxable base of up to EUR 500 million. As of 1 January 2025, there is progressive net wealth tax based solely on the company's total balance sheet size, regardless of asset composition: • €535 for companies with a total balance sheet up to and including €350,000 • €1,605 for companies with a total balance sheet between €350,001 and €2,000,000 • €4,815 for companies with a total balance sheet exceeding €2,000,000 |
| Withholding tax on dividends | Not subject to withholding tax. | Not subject to withholding tax. | Not subject to withholding tax. | Not subject to withholding tax. | Not subject to withholding tax. | Dividends distributed by a Luxembourg company are in principle subject to withholding tax at a rate of 15%, unless a domestic law exemption or a lower tax treaty rate applies. |
| Benefit from Double Tax Treaty network | • SICAV/SICAF: Limited to certain double tax treaties (see circular L.G. -A n°61 of the tax administration of 24 December 2024). • FCP: see circular L.G.-A n°61 of the tax administration of 24 December 2024. | Yes in case the SICAR is set-up as a corporate entity (except if set-up under the form of a SCS/SCSp). | • RAIFs investing in a portfolfio of risk capital (such as a SICAR) Access if set-up as a corporate entity (except if set-up under the form of a SCS/SCSp). • RAIFs not investing in a portfolio of risk capital (such as a SICAR), but set-up as: SICAV / SICAF: Limited to certain double tax treaties (see circular L.G. -A n°61 of the tax administration of 24 December 2024). FCP: see circular L.G.-A n°61 of the tax administration of 24 December 2024. | No. | No. | Yes. |
| Benefit from the EU Parent Subsidiary Directive | No. | In principle yes, but certain jurisdictions where the target companies are located may challenge the application of the directive. | No, unless RAIF that invests in a portfolio of risk capital (such as a SICAR). | No. | No. | Yes. |

CSSF Circular 25/901: Consolidated supervisory framework for SIFs, SICARs and Part II UCIs in Luxembourg
Executive Summary (at a glance)
- Scope:
Applies to SIFs, SICARs and Part II UCIs (and their compartments), excluding ELTIFs, MMFs, EuVECAs, EuSEFs and certain closed-ended funds or compartments authorised before 19 December 2025. - Continuity:
The circular does not call into question the rules adopted by the funds or compartments authorised by the CSSF before 19 December 2025. - Application going forward:
New funds, new compartments and material changes are expected to comply with Circular 25/901 as from 19 December 2025 (except for those outside the scope of the Circular).
- Risk-spreading:
Investment limits and borrowing parameters are calibrated to the target investor base, with higher flexibility for funds reserved to well-informed or professional investors.
- SICARs:
The criteria for qualifying investments as risk capital are consolidated and clarified.
- Single reference text:
Circular 25/901 replaces several prior CSSF and IML circulars, consolidating the supervisory framework.
1. Introduction / Background
On 19 December 2025, the CSSF published (i) Circular CSSF 25/901 (the “Circular”) and (ii) a separate Concepts Compilation (the “Concepts Compilation”).
The Circular consolidates and modernises the CSSF’s supervisory expectations applicable to specialised investment funds (SIFs), investment companies in risk capital (SICARs) and undertakings for collective investment subject to Part II of the Law of 17 December 2010 (Part II UCIs), including their compartments. It brings together, in a single reference text, a number of existing supervisory positions previously set out in separate CSSF and IML circulars.
2. Scope and continuity
Circular 25/901 applies to SIFs, SICARs and Part II UCIs and their compartments, with exclusions notably for funds/compartments that qualify as ELTIFs, MMFs, EuVECAs or EuSEFs, as well as certain closed-ended funds/compartments authorised before 19 December 2025.
Importantly, the Circular expressly states that it does not call into question the rules already adopted by funds or compartments authorised by the CSSF prior to its entry into force, which may continue to apply those rules.
Below you can see a recap table:
| In scope of Circular 25/901 | Out of scope of Circular 25/901 |
| · SIFs (and their compartments) ;
· SICARs (and their compartments) ; and · Part II UCIs (and their compartments)
|
· UCITS ;
· Money Market Funds (MMFs) ; · ELTIFs ; · EuVECA ; · EuSEF · Closed-ended funds or compartments that were authorised before 19 December 2025.
|
| NOTE
· While the Circular does not apply to closed-ended funds or compartments authorised before 19 December 2025, it also confirms, more broadly, that the rules already adopted by funds or compartments authorised prior to its entry into force are not called into question; ¨ · RAIFs are not within the scope of Circular 25/901; however, as further discussed in Section 10 below, the parliamentary works of the RAIF Law indicate that the principles applicable to SIFs and SICARs should be taken into account when interpreting the risk-spreading requirement for SIF like RAIFs under the RAIF regime and the risk capital concept for SICAR like RAIFs. |
|
3. Concept of assets (SIFs and Part II UCIs)
The Circular clarifies the concept of “assets” referred to in the SIF Law and the UCI Law. In principle, the concept of assets encompasses any type of investment that may be entrusted to the depositary of the SIF or of the Part II UCI for safekeeping.
Where the main objective of a SIF or a Part II UCI is to invest in assets eligible under the UCITS Directive, the Circular specifies that such fund must have an investment and borrowing policy that is different from that of a UCITS, in order to fall within the exemption provided for under the UCITS Directive.
4. Risk-spreading and diversification calibrated to the target investor base
The Circular sets out a differentiated approach to risk-spreading depending on whether a fund/compartment may be marketed to unsophisticated retail investors or whether its securities are reserved to well-informed or professional investors.
While Circular 25/901 formally applies to SIFs, SICARs and Part II UCIs, the situation where securities may be marketed to unsophisticated retail investors will, in practice, primarily concern Part II UCIs, given that SIFs and SICARs are reserved to well-informed investors under their respective product laws.
In principle, concentration limits are set at:
- 25% per issuer/undertaking for collective investment/other asset for funds or compartments whose securities may be marketed to unsophisticated retail investors; and
- 50% per issuer/undertaking for collective investment/other asset for funds or compartments whose securities are reserved to well-informed or professional investors.
For a single infrastructure investment, higher thresholds apply (up to 50% and 70% respectively), and the CSSF may grant further derogations on the basis of a duly motivated justification.
For funds or compartments whose securities may be marketed to unsophisticated retail investors, the Circular specifies that, when using financial derivative instruments, a comparable level of risk-spreading must be ensured through an appropriate diversification of the underlying assets and that counterparty risk which is not cleared by a clearing institution or not mitigated by collateral must be limited having regard to the quality and qualification of the counterparty.
Where investments are made through intermediary vehicles, regardless of their legal form, the investment limits apply to the investments made through such vehicles and not to the vehicles themselves.
5. Ramp-up and wind-down periods for private investment strategies
Recognising the realities of portfolio construction and realisation, the Circular confirms that the sales document may provide that investment limits do not apply during certain periods.
In principle:
- where the main objective of the fund or compartment is to invest in UCITS-eligible assets, the ramp-up period may last up to 12 months from launch; and
- where the fund or compartment pursues private investment strategies, the ramp-up period may be longer but may not, in principle, exceed four years, subject to a possible duly justified extension accepted by the CSSF.
Where the objective of the fund or compartment is to make private investments, the sales document may also provide that investment limits cease to apply during the wind-down period.
During these periods, the fund or compartment must not be exposed to excessive risks or conflicts of interest that had not been previously identified, and available cash may only be invested in accordance with the sales document.
6. Borrowing
SIFs and Part II UCIs may borrow cash to make investments, cover costs and expenses or meet redemptions, and may encumber assets when borrowing.
Where a fund or compartment may be marketed to unsophisticated retail investors, borrowing for investment purposes must, in principle, not exceed 70% of assets or commitments to subscribe. Where securities are reserved to well-informed or professional investors, no fixed borrowing cap applies, and the fund or compartment sets its own maximum borrowing limit.
Temporary borrowing arrangements that are fully covered by investors’ capital commitments are, in principle, not regarded as borrowings.
Any intended borrowing must be disclosed in the sales document, including the applicable borrowing limit.
7. SICARs: clearer articulation of the “risk capital” assessment
For SICARs, the Circular consolidates and clarifies the CSSF’s approach to assessing whether investments qualify as risk capital, including:
- an intention to contribute to the development of the target entity;
- the existence of a specific risk exceeding mere market risk;
- an exit strategy; and
- where appropriate, a degree of control or supervision over the target entity.
The Circular emphasises that a purely passive holding approach is not acceptable and that the assessment of risk capital is driven by the economic substance of the investment and the development objective, rather than by purely formal or legal criteria.
8. Consolidation: fewer legacy references, one supervisory point of reference
Circular 25/901 repeals and replaces several earlier CSSF and IML circulars, consolidating the relevant supervisory expectations into a single reference text for these regulated fund regimes.
9. The Concepts Compilation – explanatory reference
As stated in Circular CSSF 25/901, for the illustration of the general concepts underlying the Circular, reference is made to the document entitled “Compilation of the key concepts and terms used in the area of investment funds other than UCITS and MMFs and how the CSSF understands them”, which is updated on a regular basis.
The Concepts Compilation is an explanatory document published by the CSSF that clarifies certain commonly used concepts and terms and explains how the CSSF understands them. It is neither a regulation nor a CSSF circular, does not purport to be exhaustive and does not prejudge the acceptability of any application for authorisation, without prejudice to the applicable European and Luxembourg legal and regulatory framework and to the relevant sales documents.
10. Considerations for Luxembourg RAIFs
Reserved alternative investment funds (RAIFs) are not within the scope of Circular CSSF 25/901, as they are not subject to prior authorisation or direct supervision by the CSSF.
That being said, the Law of 23 July 2016 on reserved alternative investment funds (the “RAIF Law”) was drafted by reference to the SIF and SICAR regimes and incorporates the same core product concepts.
SIF-like RAIFs – Risk-spreading
Article 1(1)(b) of the RAIF Law provides that a RAIF must have as its sole object the collective investment of its funds in assets “with the aim of spreading the investment risks and giving investors the benefit of the results of the management of their assets.”
The RAIF Law does not further define the concept of spreading investment risks.
The parliamentary works clarify that, in the absence of specific statutory guidance, RAIFs and/or their representatives may refer to the framework developed for SIFs, notably the diversification guidance previously set out in Circular CSSF 07/309, for the interpretation of this concept.
SICAR-like RAIFs – Risk capital
Article 48(1) of the RAIF Law provides that a RAIF may state in its constitutive documents that its exclusive object is the investment of its funds in assets representing risk capital. In that case, by way of derogation from Article 1, the RAIF is not required to spread investment risks.
Investment in risk capital is defined, in wording identical to Article 1(2) of the SICAR Law, as the direct or indirect contribution of assets to entities in view of their launch, development or listing on a stock exchange.
The RAIF Law does not provide further clarification of this notion. The parliamentary works indicate that RAIFs, their representatives and their approved statutory auditor may refer to the framework developed for SICARs, notably Circular CSSF 06/241, for the interpretation of the concept of risk capital.
Relevance of Circular 25/901 for RAIFs
Circular CSSF 25/901 repeals and replaces, inter alia, Circulars 07/309 (SIF risk-spreading) and 06/241 (SICAR risk capital), consolidating the supervisory framework applicable to SIFs and SICARs into a single reference text.
Although Circular 25/901 does not formally apply to RAIFs, the legislative structure of the RAIF regime which mirrors the substantive product concepts of the SIF and SICAR frameworks while dispensing with product-level CSSF authorisation suggests that the interpretation of the notions of risk-spreading and risk capital under the RAIF Law is expected to remain aligned with the consolidated framework now applicable to SIFs and SICARs.
11. Practical implications for fund sponsors and managers
Circular CSSF 25/901 aims to provide greater clarity and consistency in the supervisory framework applicable to SIFs, SICARs and Part II UCIs.
As expressly stated in the Circular, funds and compartments authorised by the CSSF prior to 19 December 2025 are not required to amend their existing arrangements and may continue to apply the rules previously approved by the CSSF.
As from 19 December 2025, the Circular will serve as the primary supervisory reference for the CSSF. In practice, it will be particularly relevant in the context of:
- the launch of new SIFs, SICARs or Part II UCIs;
- the creation of new compartments; and
- material changes implemented after that date, including changes to investment policies, risk-spreading parameters, borrowing arrangements or related disclosures.
The Circular also confirms a calibrated approach based on the target investor base, allowing greater flexibility for products reserved to well-informed or professional investors, while setting clearer parameters where a fund or compartment may be marketed to unsophisticated retail investors.
Overall, Circular CSSF 25/901 should be viewed as a consolidation and clarification exercise, preserving continuity for existing structures while providing a clearer supervisory framework for future developments.
12. How can we assist you?
We would be pleased to assist you in assessing the implications of Circular CSSF 25/901 for your existing or planned structures, including in the context of new fund launches, the creation of new compartments or changes to existing products, and in aligning documentation and operational policies with the CSSF’s consolidated supervisory framework.
Please feel free to contact our Investment Management team should you wish to receive further information or discuss the impact of Circular CSSF 25/901 on your structures.

Comparison table of Luxembourg alternative investment funds (AIFs) and other investment vehicles
Compare two vehicles:
| UCITS | Part II UCI | ELTIF | SIF | SICAR | RAIF | SPF | Securitisation vehicle | Unregulated SCS/SCSp | SOPARFI | |
|---|---|---|---|---|---|---|---|---|---|---|
| English name/description | Undertakings for collective invesment in transferable securities | Part II Undertaking for Collective Investment | European long-term investment fund | Specialised Investment Fund | Investment Company in Risk Capital | Reserved Alternative Investment Fund | Private Wealth Management Company | Securitisation vehicle | Unregulated common limited partnership/special limited partnership | SOPARFI |
| Practical use | Highly regulated investment vehicle authorised by the CSSF and eligible for cross-border marketing within the EU under the UCITS passport, which may be marketed to retail, professional and institutional investors, subject to applicable requirements. | CSSF-authorised regulated investment vehicle used for investment strategies that fall outside the the UCITS eligibility criteria, including strategies involving less liquid or non-UCITS-eligible assets, while remaining subject to full CSSF product supervision. | EU long-term investment fund label applicable to investment vehicles investing in long-term assets forming part of the real economy, such as private equity, infrastructure, real assets and private debt, and designed to facilitate long-term investment strategies, including, subject to applicable conditions, access by retail investors. | CSSF-authorised regulated alternative investment vehicle reserved to well-informed investors and commonly used as an AIF for a broad range of alternative investment strategies, including private equity, hedge funds, real estate, infrastructure and private debt. | CSSF-authorised regulated investment vehicle dedicated to private equity, venture capital and other investments qualifying as risk capital, targeting the development and value creation of portfolio companies. | Alternative investment vehicle reserved to well-informed investors, used for the same range of alternative investment strategies as SIFs, including hedge funds, private equity, venture capital, real estate, infrastructure and private debt, and structured without prior CSSF product authorisation, with regulatory supervision exercised by the CSSF at the level of the authorised AIFM. | Unregulated investment vehicle used by individuals for private wealth structuring and the holding of financial assets, limited to passive asset management and excluded from any commercial or professional investment activity. | Investment vehicle used for securitisation transactions, including true sale and synthetic securitisations, securitisation of portfolios of securities or receivables (such as loans, leasing receivables and non-performing loans), securitisation of tangible and intangible assets, intra-group financing structures, and structured finance transactions such as collateralised loan obligations (CLOs), including, where applicable, actively managed structures. | Unregulated partnership investment vehicle commonly used for private equity, real estate, venture capital and other alternative strategies, offering significant contractual flexibility and frequently used in fund structuring, co-investment arrangements and carried interest vehicle structures. | Ordinary Luxembourg corporate vehicle commonly used for holding, financing and investment activities, including the holding of participations, intra-group financing, intellectual property holding and other investment activities, depending on the structure and purpose. |
| Applicable legislation | Law of 17 December 2010 - Part I (“UCITS Law”). | Law of 17 December 2010 - Part II (“UCI Law”). | Regulation (EU) 2015/760 of 29 April 2015 on European long-term investment funds (“ELTIF Regulation”), amended on 15 March 2023 . ("ELTIF 2 Regulation"). | Law of 13 February 2007 (“SIF Law”). | Law of 15 June 2004 (“SICAR Law”). | Law of 23 July 2016 (“RAIF Law”). | Law of 11 May 2007 (“SPF Law”). | Law of 22 March 2004 (“Securitisation Law”). | Law of 10 August 1915 (“Company Law”). | Law of 10 August 1915 (“Company Law”). |
| Authorisation and supervision by the CSSF | Yes. | Yes. | Yes. | Yes. | Yes. | No. | No. | No, unless issue on a continuous basis of financial instruments offered to the public. The securitisation vehicle issues on a continuous basis when it carries out more than three issuances of financial instruments offered to the public during the financial year. All the issuances by the compartments should be added up. The issuance of financial instruments is offered to the public when it is not intended for professional clients, the denominations are less than EUR 100,000 and it is not distributed as private placement. | Non. | Non. |
| Qualification as an AIF | No. | Always an AIF. | Always an AIF. | Yes, unless it falls outside the AIF definition (i.e. it does not raise capital from a number of investors, with a view to investing it in accordance with a defined investment policy for the benefit of those investors). | Yes, unless it falls outside the AIF definition (i.e. it does not raise capital from a number of investors, with a view to investing it in accordance with a defined investment policy for the benefit of those investors). | Always an AIF. | In principle, no (as it would not be considered as “raising” capital from a number of investors as the structure generally serves for the investment of the private wealth of a “pre-existing group” (as defined in the Esma guidelines on key concepts of the AIFMD)). | No, in case • such vehicle meets the definition of “securitisation special purpose vehicle ” under the AIFM Law; • it issues collateralised debt obligations; • it only issues debt instruments; • such entity is not managed according to an investment policy within the meaning of the AIFM Law. | Non-AIF, unless activities fall within the scope of article 1 (39) of the AIFM Law. | Non-AIF, unless activities fall within the scope of article 1 (39) of the AIFM Law. |
| Exemption from AIFMD full regime under lighter regime (AIFMD registration regime) | Not applicable. | Possible. | No. | Possible. | Possible. | No. | Not applicable. | Possible. | Possible. | Possible. |
| External authorised AIFM requirement | Not applicable. | Required in case the entity is an AIF that is not self-managed and above the AIFMD threshold. | Required in case the entity is an AIF that is not self-managed. Always an authorised EU AIFM. | Required in case the entity is an AIF that is not self-managed and above the AIFMD threshold. | Required in case the entity is an AIF that is not self-managed and above the AIFMD threshold. | Always required. | Not applicable. | Required in case the entity is an AIF that is not self-managed and above the AIFMD threshold. | Required in case the entity is an AIF that is not self-managed and above the AIFMD threshold. | Required in case the entity is an AIF that is not self-managed and above the AIFMD threshold. |
| Eligible investors | Unrestricted. | Unrestricted. | Unrestricted. | Well-informed investors, namely institutional or professional investors (MiFID II), or other investors who confirm their status in writing and either invest at least EUR 100,000 or are assessed by a credit institution, investment firm, UCITS ManCo or authorised AIFM as having sufficient expertise, experience and knowledge. | Well-informed investors, namely institutional or professional investors (MiFID II), or other investors who confirm their status in writing and either invest at least EUR 100,000 or are assessed by a credit institution, investment firm, UCITS ManCo or authorised AIFM as having sufficient expertise, experience and knowledge. | Well-informed investors, namely institutional or professional investors (MiFID II), or other investors who confirm their status in writing and either invest at least EUR 100,000 or are assessed by a credit institution, investment firm, UCITS ManCo or authorised AIFM as having sufficient expertise, experience and knowledge. | Restricted to: • natural persons acting in the context of the management of their personal wealth; • management entities acting solely in the interest of the private wealth (e.g. trusts, private foundations); and intermediaries acting for the account of the above mentioned eligible investors (e.g. bank acting under a fiduciary agreement). | Unrestricted. | Unrestricted. | Unrestricted. |
| Eligible assets | Restricted to transferable securities admitted or dealt on a regulated market, investment funds, financial derivative instruments, cash and money market instruments that are in compliance with article 41 of the Ucits law and the relevant EU directives and regulations. Please note that the eligibility of the asset must be ascertained on a case-by-case basis in view of the applicable laws and regulatory practice. | Unrestricted. The investment objective and strategy of the fund is subject to the prior approval of the CSSF. | Restricted to: - equity or quasi-equity instruments and debt instruments issued by a qualifying portfolio undertaking; -loans granted by the ELTIF to a qualifying portfolio undertaking with a maturity that does not exceed the life of the ELTIF, - units or shares of one or several other ELTIFs, EuVECAs, EuSEFs, UCITS and EU AIFs managed by EU AIFM provided that those ELTIFs, EuVECAs, EuSEFs¸ UCITS and EU AIFs invest in eligible investments (this wording) and have not themselves invested more than 10% of their assets in any other UCI; - real assets; - certain STS securitisations (where the underlying exposures are residential mortgage-backed securities, commercial loans backed by mortgages on commercial immovable property, credit facilities, trade receivables and other underlying exposures; provided that, for the two last ones, the proceeds from the securitisation bonds are used for financing or refinancing long-term investments), - EU Green Bonds issued by a qualifying portfolio, and UCITS eligible assets. Qualifying portfolio undertaking is an undertaking that fulfils, at the time of the initial investment, the following requirements: - it is not a financial undertaking undertaking, unless it is a financial undertaking, other than a financial holding company or a mixed-activity holding company, that has been authorized or registered more recently than 5 years before the date of the investment (fintechs); - is not admitted to trading on a regulated market or on a multilateral trading facility; or is admitted to trading on a regulated market or on a multilateral trading facility and has a market capitalisation of no more than EUR 1 500 000 000; - it is established in a Member State, or in a third country provided that the third country is not identified as high-risk third and is not mentioned in the EU list of non-cooperative jurisdictions for tax prusposes. ELTIFs are not allowed to: - short sell - take direct or indirect exposure to commodities; - enter into securities lending, securities borrowing, repurchase transactions, or any other agreement which has an equivalent economic effect and poses similar risks, if more than 10 % of the assets of the ELTIF are affected; - use financial derivative instruments, except where the use of such instruments solely serves the purpose of hedging the risks inherent to other investments of the ELTIF. | Unrestricted. The investment objective and strategy of the fund is subject to the prior approval of the CSSF. | Restricted to investments in securities representing risk capital as specified in CSSF Circular 25/901 which has replaced Circular 06/241. The circular clarifies the criteria applied by the CSSF when assessing whether investments pursued by a SICAR qualify as risk capital, notably the intention to develop the target entity, the existence of a specific risk going beyond mere market risk, an exit strategy and, where appropriate, a degree of control or supervision A SICAR may use derivatives for hedging purposes or if such transactions are necessary to the realisation of its investment policy. However, investments in derivatives may not be the object of its investment policy, as they are not used, in principle, to create value in itself or to contribute to the development of the target entity. The investment of a SICAR in real estate is only possible through intermediary vehicles (such as SPVs) or real-estate funds. The underlying real-estate assets must meet the criteria of risk capital set out in CSSF circular 25/901. | Unrestricted, unless the RAIF is established as a SICAR-type RAIF investing exclusively in risk capital. | Restricted to acquisition, detention, management and realisation of financial assets. The SPF is not allowed to carry out commercial activities or to hold directly real estate (except for its own use or through its participations). | Unrestricted. The securitisation vehicle may acquire or assume, directly or through another undertaking, risks relating to claims, other assets, or obligations assumed by third parties or inherent to all or part of the activities of third parties and issues financial instruments or contracts, for all or part of it, any type of loan, whose value or yield depends on such risks. | Unrestricted. | Unrestricted. |
| Risk diversification requirements | Risk diversification requirements are provided by articles 42 et seq. of the UCITS Law, e.g. (not exhaustive): • a UCITS may not invest more than 10% of its assets in transferable securities or money market instruments issued by the same body; • a UCITS may not invest more than 20% of its net assets in deposits made with the same body; • the global exposure relating to derivative instruments does not exceed the total net value of the UCITS portfolio. | Risk diversification requirements applicable to Part II UCIs are set out in CSSF Circular 25/901, which specifies the concept of risk-spreading referred to in Articles 89(1), 93(1) and 97 of the Law of 17 December 2010. In principle, Part II UCIs marketed to unsophisticated retail investors may not invest more than 25% of their assets or commitments to subscribe in a single issuer, entity or asset, subject to specific derogations. For Part II UCIs reserved to well-informed or professional investors, this limit is raised to 50%, and up to 70% for a single infrastructure investment. The circular allows for duly justified derogations and provides for ramp-up and, where applicable, wind-down periods during which investment limits may not apply, subject to CSSF acceptance. | Risk diversification requirements are provided by articles 13 and 17 of the ELITF Regulation (not exhaustive): ELTIFs marketed to retail investors shall not invest more than: - 20 % of its capital in instruments issued by, or loans granted to, any single qualifying portfolio undertaking; - 20 % of its capital in a single real asset; - 20 % of its capital in units or shares of any single ELTIF, EuVECA, EuSEF, UCITS, or EU AIF managed by an EU AIFM; - 10 % of its capital in UCITS (liquid) assets where those assets have been issued by any single body; or 25 % where bonds are issued by a credit institution which has its registered office in a Member State and is subject by law to special public supervision designed to protect bond-holders; - The aggregate value of STS Securitisations in an ELTIF portfolio shall not exceed 20% of the value of the capital of the ELTIF; - The aggregate risk exposure to a counterparty of the ELTIF stemming from OTC derivative transactions, repurchase agreements, or reverse repurchase agreements shall not exceed 10 % of the value of the capital of the ELTIF. | Risk diversification requirements are set out in CSSF Circular 25/901. For SIFs and compartments thereof reserved for well-informed or professional investors, the following concentration limits apply - a maximum of 50% of assets may be invested in a single issuer, entity, or asset; - a higher limit of up to 70% applies to a single infrastructure investment. The circular also allows a defined ramp-up period and a wind down period up to 4 years for private investments, during which limits may not apply as described in the sales document. | No risk diversification requirements. A SICAR may set investment limits in its sales document and may include ramp up and wind down periods during which those self-imposed limits do not apply. | Aligned with SIF risk diversification rules, unless the RAIF has opted to invest exclusively in risk capital and is therefore subject to the SICAR regime, as stated in its constitutive documents. | No risk diversification requirements. | No risk diversification requirements. | No risk diversification requirements. | No risk diversification requirements. |
| Legal form | • FCP • SICAV (SA) • SICAF (SA,SCA) All of these entities must be open-ended. | • FCP • SICAV (SA) • SICAF (SA, Sàrl, SCA, SCS, SCSp) The entities may be open-ended or closed-ended. | • FCP, SICAV and SICAF in various legal forms, Soparfis, SCS, SCSp, SCA and future forms entitling an AIF to be authorized as an ELTIF. In principle closed-ended, but may be open-ended provided certain safeguards are set up, inter alia: - redemptions are not granted before the end of a minimum holding period or before the date specified in the rules or instruments of incorporation - at the time of authorisation and throughout the life of the ELTIF, the manager is able to demonstrate that the ELTIF has an appropriate redemption policy and LMTs compatible with the long-term strategy of the ELTIF. | • FCP • SICAV (SA, Sàrl, SCA, SCoSA, SCS, SCSp) • SICAF (SA, Sàrl, SCA, SCoSA, SCS, SCSp) The entities may be open-ended or closed-ended. | • SA • Sàrl • SCA • SCS • SCSp • SCoSA The entities may be open-ended or closed-ended. | • FCP • SICAV (SA, Sàrl, SCA, SCoSA, SCS, SCSp) • SICAF (SA, Sàrl, SCA, SCoSA, SCS, SCSp) The entities may be open-ended or closed-ended. | • SA • Sàrl • SCA • SCSA | A securitisation vehicle may be set up in one of the following forms: • a securitisation company (SA, Sàrl, SCS, SCSp, SENC, SCA, SAS, SCSA); or • a securitisation fund consisting of one or several co-ownerships or one or several fiduciary estates and managed by a management company. | • SCS • SCSp | • SA, Sàrl, SCA • SAS • SCoSA • SCS • SCSp |
| Umbrella structure | Yes. | Yes. | Yes. Application for authorisation as ELTIF of one or more compartments may be submitted | Yes. | Yes. | Yes. | No. | Yes. | No. | No. |
| Capital requirements | • FCP: EUR 1,250,000 to be reached no later than 6 months following the authorisation by the CSSF. • Self managed SICAV / SICAF: EUR 300,000 at the date of authorisation and EUR 1,250,000 within 6 months following its authorisation. | • FCP: EUR 1,250,000 to be reached no later than 12 months following the authorisation by the CSSF. • Self managed SICAV / SICAF: EUR 300,000 at the date of authorisation and EUR 1,250,000 within 12 months following its authorisation. | As ELTIF is an EU label, the capital requirements applicable to an ELTIF are the capital requirements applicable to fund, in particular due to the national product law. | EUR 1,250,000 to be reached no later than 24 months following the authorisation by the CSSF. | EUR 1,000,000 to be reached no later than 24 months following the authorisation by the CSSF. | • FCP: EUR 1,250,000 to be reached within 24 months from the entry into force of the management regulations. • SICAV: EUR 1,250,000 to be reached within 24 months from the incorporation of the SICAV. | Depends on the form: • SA / SCA: EUR 30,000 • Sàrl: EUR 12,000 • SCSA: no minimum capital. | If the securitisation vehicle is set up as a company, it depends on the form: • SA / SCA: EUR 30,000 • Sàrl: EUR 12,000 If the securitisation vehicle is set up as a fund, there is no minimum capital requirement. | No minimum capital requirement. | Depends on the form: • SA / SCA: EUR 30,000 • Sàrl: EUR 12,000 No minimum capital requirement for other legal forms. |
| Required service providers | • Management company in case of an FCP. • Depositary institution. • Administrative agent. • Registrar and Transfer Agent. • Approved statutory auditor. | • Management company in case of an FCP. • Depositary institution. • Administrative agent. • Registrar and Transfer Agent. • Approved statutory auditor. • Registered AIFM or Authorised AIFM in case of an AIF above threshold. | • As ELTIF is an EU label, the required service providers for an ELTIF depend on the applicable national product law. • Management company in case of an FCP. • Depositary bank or professional of the financial sector providing depositary services, subject to conditions. However, if the ELTIF is marketed to retail investors, the Depositary shall comply with the UCITS depositary requirements and be a Depositary institution • Administrative agent. • Registrar and Transfer Agent. • Authorised AIFM. • Other service providers required by the relevant product rules. | • Registered AIFM or authorised AIFM in case of an AIF above threshold. • Management company in case of an FCP. • Depositary bank or professional of the financial sector providing depositary services, subject to conditions. • Administrative agent. • Registrar and Transfer Agent. • Approved statutory auditor. | • Registered AIFM or authorised AIFM in case of AIF above threshold. • Depositary bank or professional of the financial sector providing depositary services, subject to conditions. • Administrative agent. • Registrar and Transfer Agent. • Approved statutory auditor. | • Authorised AIFM. • Management company in case of an FCP • Depositary bank or professional of the financial sector providing depositary services, subject to conditions. • Administrative agent. • Registrar and Transfer Agent. • Approved statutory auditor. | Registered auditor in principle not required unless two of the following criteria are met: (i) net turnover above EUR 8.8 million, (ii) balance sheet above EUR 4.4 million and (iii) average number of employees above 50. However, depending on the legal form of the company, there may be an obligation to appoint a commissaire aux comptes. | • Alternative Investment Fund Manager (if the securitisation vehicle qualifies as an AIF). • Management company (if the securitisation vehicle is set up in the form of a fund). • Independent auditor. • No depository institution (unless for regulated securisation vehicles). • No administrative agent. | For SCS: • Alternative Investment Fund Manager (if the SCS qualifies as an AIF). • No requirement to appoint a depositary (except if the SCS qualifies as an AIF and is managed by a duly authorised AIFM). For SCSp: • Alternative Investment Fund Manager (if the SCSp qualifies as an AIF). • No requirement to appoint a depositary (except if the SCSp qualifies as an AIF and is managed by a duly authorised AIFM). | Registered auditor in principle not required unless the company is an AIF managed by an AIFM with AUM above the threshold or two of the following criteria are met: (i) net turnover above EUR 8.8 million, (ii) balance sheet above EUR 4.4 million and (iii) average number of employees above 50. However, depending on the legal form of the company, there may be an obligation to appoint a commissaire aux comptes. On 28 July 2023, draft bill 8286 (the Draft Bill) was released, aiming to overhaul Luxembourg accounting law applicable to undertakings (the New Law). |
| Possibility of listing | Yes. | Yes. | Yes. | Yes. | Yes, but difficult in practice. | Yes. | No. | No. | In principle, no. The SCS/SCSp may however issue debt securities that are eligible to be listed on the stock exchange. | Yes. |
| European passport | Yes. | Yes, but needs to fall under the scope of the full AIFMD regime. | Yes. | Yes, but needs to fall under the scope of the full AIFMD regime. | Yes, but needs to fall under the scope of the full AIFMD regime. | Yes (always under the full AIFMD regime). | No. | No, unless it falls under the scope of the full AIFMD regime. | No, unless it falls under the scope of the full AIFMD regime. | No, unless it falls under the scope of the full AIFMD regime. |
| Net asset value (NAV) calculation and redemption frequency | The UCITS must make public the issue, sale and repurchase price of their units each time they issue, sell and repurchase their units, and at least twice a month. | The UCIs must make public the issue, sale and repurchase price of their units each time they issue, sell and repurchase their units, and at least once a month. | The UCIs must make public the issue, sale and repurchase price of their units each time they issue, sell and repurchase their units, and at least once a month. As ELTIF is an EU label, the NAV computation and redemption frequency depend on applicable national product law and the AIFM law. At least once a year for reporting purposes. Redemption frequency: In principle closed-ended, but may be open-ended provided certain safeguards are set up, inter alia: - redemptions are not granted before the end of a minimum holding period or before the date specified in the rules or instruments of incorporation - at the time of authorisation and throughout the life of the ELTIF, the manager is able to demonstrate that the ELTIF has an appropriate redemption policy and LMTs compatible with the long-term strategy of the ELTIF; - redemptions are limited to a percentage of the UCITS (liquid) assets of the ELTIF. An ELTIF may offer, under certain conditions, early redemption rights to its investors according to the ELTIF's investment strategy. | At least once a year. | The valuation of the assets of the company is based on the "fair value". | At least once a year. | Not required. | Not required. | Not required. | Not required. |
| Borrowings / leverage limits | Borrowings of up to 10% of net assets to finance redemptions (it should be a short term borrowing and cannot be for investment purposes) or to buy real estate for its business. The total borrowing under the above may not exceed 15% of net assets. | Part II UCI may borrow cash. Where borrowing is used for investment purposes and the fund or compartment is marketed to unsophisticated retail investors, borrowing must, in principle, not exceed 70% of its assets or commitments to subscribe. Where the fund or compartment is reserved to well-informed or professional investors, this limit does not apply and the maximum borrowing level is determined by the fund and disclosed in its sales document. | As ELTIF is an EU label, there is no harmonised EU-level debt-to-equity ratio and any product-specific leverage constraints depend on the national rules applicable to the AIF. Borrowings of cash of up to 50% of the NAV of the ELTIF marketed to retail investors and up to 100% for the ELTIF marketed solely to professional investors. | No debt-to-equity ratio. According to circular 25/901, SIFs may borrow cash for investment and operational purposes. The Fund or compartment may set its own borrowing limits. | No debt-to-equity ratio. CSSF Circular 25/901, limits the use of borrowing in consideration to the specific objective of the SICAR. Reference should be made to the general principles laid down in Chapter 5 of the circular. When borrowing cash, the fund or the compartment may encumber assets. | No debt-to-equity ratio. | Tax of 0.25% on the debt that exceeds 8 times the paid-up capital increased by the issue premium. | No debt-to-equity ratio. | No debt-to-equity ratio. | No provision in Luxembourg law. However, there is a specific administrative practice. |
| Overall income tax (corporate income tax and municipal business tax) | No income tax. | No income tax. | As ELTIF is an EU label the tax treatment depends on the national product rules applicable to the AIF. | No income tax. | • General aggregate rate: 23.87%. In certain cases, reduced corporate income tax rates may apply. Income derived from transferable securities (e.g. dividends received and capital gains realised on the sale of shares) is exempt. Income on cash held for the purpose of a future investment is also exempt (for one year). | No income tax, unless investing only in risk capital, then SICAR tax regime applicable. | No income tax. | • General aggregate rate for taxable securisation companies: 23.87%. Securitisation vehicles should be able to deduct from their gross profits their operational costs and the dividends or interests distributed to the shareholders/creditors. Therefore securitisation companies should not generate significant taxable profits and should therefore to a large extent be tax neutral. | No corporate income tax applicable. Municipal business tax of 6.75% applicable in very limited circumstances, namely in case the SCS/SCSp (i) carries out a commercial activity or (ii) is deemed to carry out a commercial activity. A SCS/SCSp is deemed to carry out a commercial activity if its general partner is a Luxembourg public or private limited liability company holding at least 5% of the partnership interests. With a proper structuring of the GPs partnership interest it should be possible to avoid the deemed commercial characterisation of the SCS/SCSp. | General aggregate rate: 23.87%, but 100% exemption for dividends, liquidation proceeds and capital gains from qualifying participations. |
| Subscription tax (NAV: net asset value) | • Rate: 0.05% of the NAV annually. • Reduction: 0.01% of the NAV annually in certain specific cases. • Where the proportion of net assets of a UCITS or one of its compartments in certain Taxonomy-sustainable activities represents at least 5 per cent of the aggregate net assets of the UCITS or of its relevant compartment, the subscription tax rate is 0.04 per cent. Where the proportion of such assets is at least 20 per cent, this rate amounts to 0.03 per cent. Where the proportion is at least 35 %, the subscription tax rate amounts to 0.02 per cent. Where the proportion is at least 50 per cent, this rate amounts to 0.01 per cent. However, net assets in nuclear energy and fossil gaseous fuel are excluded from such decreased rates. • Tax exemptions: special institutional money market cash funds, special pension funds (including pension pooling vehicles) and funds investing in other funds which are already subject to subscription tax. | • Rate: 0.05% of the NAV annually. • Reduction: 0.01% of the NAV annually in certain specific cases. • Where the proportion of net assets of a UCITS or one of its compartments in certain Taxonomy-sustainable activities represents at least 5 per cent of the aggregate net assets of the UCITS or of its relevant compartment, the subscription tax rate is 0.04 per cent. Where the proportion of such assets is at least 20 per cent, this rate amounts to 0.03 per cent. Where the proportion is at least 35 %, the subscription tax rate amounts to 0.02 per cent. Where the proportion is at least 50 per cent, this rate amounts to 0.01 per cent. However, net assets in nuclear energy and fossil gaseous fuel are excluded from such decreased rates. • Tax exemptions: special institutional money market cash funds, special pension funds (including pension pooling vehicles) and funds investing in other funds which are already subject to subscription tax. | As ELTIF is an EU label the tax treatment depends on the national product rules applicable to the AIF. | • Rate: 0.01% of the NAV annually. • Tax exemptions: certain money market and pension funds or SIFs investing in other funds which are already subject to subscription tax. | No subscription tax. | • Rate: 0.01% of the NAV annually. • Exemptions apply. | Annual subscription tax of 0.25% on the amount of paid up capital and issue premium (if any). | No subscription tax. | No subscription tax. | No subscription tax. |
| Wealth tax | No wealth tax. | No wealth tax. | As ELTIF is an EU label the tax treatment depends on the national product rules applicable to the AIF. | No wealth tax. | No wealth tax. | No wealth tax. | No wealth tax. | No wealth tax. | No wealth tax. | 0.5% on a taxable base of up to EUR 500 million. As of 1 January 2025, there is progressive net wealth tax based solely on the company's total balance sheet size, regardless of asset composition: • €535 for companies with a total balance sheet up to and including €350,000 • €1,605 for companies with a total balance sheet between €350,001 and €2,000,000 • €4,815 for companies with a total balance sheet exceeding €2,000,000 |
| Withholding tax on dividends | Not subject to withholding tax. | Not subject to withholding tax. | As ELTIF is an EU label the tax treatment depends on the national product rules applicable to the AIF. | Not subject to withholding tax. | Not subject to withholding tax. | Not subject to withholding tax. | Not subject to withholding tax. | Not subject to withholding tax. | Not subject to withholding tax. | Dividends distributed by a Luxembourg company are in principle subject to withholding tax at a rate of 15%, unless a domestic law exemption or a lower tax treaty rate applies. |
| Benefit from Double Tax Treaty network | • SICAV/SICAF: Limited to certain double tax treaties (see circular L.G. -A n°61 of the tax administration of 24 December 2024). • FCP: see circular L.G.-A n°61 of the tax administration of 24 December 2024. | • SICAV/SICAF: Limited to certain double tax treaties (see circular L.G. -A n°61 of the tax administration of 24 December 2024). • FCP: see circular L.G.-A n°61 of the tax administration of 24 December 2024. | As ELTIF is an EU label the tax treatment depends on the national product rules applicable to the AIF. | • SICAV/SICAF: Limited to certain double tax treaties (see circular L.G. -A n°61 of the tax administration of 24 December 2024). • FCP: see circular L.G.-A n°61 of the tax administration of 24 December 2024. | In principle yes in case the SICAR is set-up as a corporate entity (except if set-up under the form of a SCS/SCSp). | • RAIFs investing in a portfolfio of risk capital (such as a SICAR) Access if set-up as a corporate entity (except if set-up under the form of a SCS/SCSp). • RAIFs not investing in a portfolio of risk capital (such as a SICAR), but set-up as: SICAV / SICAF: Limited to certain double tax treaties (see circular L.G. -A n°61 of the tax administration of 24 December 2024). FCP: see circular L.G.-A n°61 of the tax administration of 8 December 2024. | No. | Yes for securitisation companies. | No. | Yes. |
| Benefit from the EU Parent Subsidiary Directive | No. | No. | As ELTIF is an EU label the tax treatment depends on the national product rules applicable to the AIF. | No. | In principle yes, but certain jurisdictions where the target companies are located may challenge the application of the directive. | No, unless RAIF that invests in a portfolio of risk capital (such as a SICAR). | No. | Yes. | No. | Yes. |
Setting up a Luxembourg RAIF
Factsheet RAIF
Discover how and why to establish a RAIF in Luxembourg. Download the fact sheets in your preferred language here:



A detailed guide to the Luxembourg RAIF
For a detailed and in-depth understanding of RAIFs in Luxembourg, we have prepared a comprehensive brochure in English. Click here to download our RAIF brochure and gain valuable insights into the features, benefits, and regulatory aspects of RAIFs. Empower yourself with the knowledge to make informed investment decisions in the world of RAIFs.
Law of 21 July 2023: Modernizing Luxembourg's Investment Fund toolbox and its impact on RAIF, SIF, SICAR, AIFM & UCI
Luxembourg has taken a significant stride towards modernizing its investment fund laws with the entry into force of the law of 21 July 2023 on 28 July 2023. It adopted Bill 8183 by the Luxembourg Parliament. This law introduces amendments to several pivotal fund laws, including the Law of 2010 on Undertakings for Collective Investment (UCI Law), the Law of 2007 on Specialized Investment Funds (SIF Law), the Law of 2004 on Investment Companies in Risk Capital (SICAR Law), the Law of 2013 on Alternative Investment Fund Managers (AIFM Law), and the Law of 2016 on Reserved Alternative Investment Funds (RAIF Law). These amendments are designed to update and strengthen the country’s fund-related regulations, bolstering the competitiveness and attractiveness of Luxembourg’s financial centre.
The adopted amendments encompass several significant changes, including inter alia:
1. Undertakings for Collective Investment (UCITS and UCI Part II)
| New regime introduced by the law of 21 July 2023 | Previous regime under UCI Law | |
|---|---|---|
| Timeframe for reaching the minimum capital | The period for achieving subscribed capital has been extended to 12 months for UCIs Part II. | The period for achieving subscribed capital was 6 months for UCIs Part II. |
| Replacement of depositary | The depositary agreement must include prior notice provisions, and a replacement depositary must be appointed before the expiry of this notice period. During this transition period, outgoing depositaries are still required to safeguard the interests of investors. This change mitigates the risk of automatic de-listing, considering the necessary time for conducting due diligence and onboarding a new depositary. | A 2-month maximum period was previously foreseen to replace a depositary. |
| Suspension of subscription and/or redemption | Subscriptions and/or redemptions of a SICAV are prohibited: - for the period during which there is no depositary; or - when the depositary is in liquidation, declared bankrupt or undergoing a suspension of payments, an arrangement with its creditors or some other type of management supervision. | The prohibition of subscription and/or redemption of a SICAV for the period during which there was no depositary or when the depositary was in liquidation, declared bankrupt or undergoing a suspension of payments, an arrangement with its creditors or some other type of management supervision was not foreseen under the previous regime. |
| Formation | UCIs Part II opting for a corporate form as SICAV may take the form of a public limited liability company (SA), corporate partnerships limited by shares (SCA), common and special limited partnerships (SCS/SCSp), private limited liability companies (SARL), as well as cooperatives organized as public companies limited by shares (SCoSA). | UCIs Part II opting for a corporate form as SICAV may take the form of a public limited liability company (SA). |
| Issuance share/interests | Closed-ended UCIs Part II may issue shares/interests at a price other than the NAV, provided it is stated in the constitutive documents. | Closed-ended UCIs Part II may issue shares/interests at a NAV price. |
| Tax | i. UCIs Part II authorized as ELTIF are exempted from subscription tax ii. UCIs Part II reserved to PEPPs are exempted from subscription tax iii. UCIs Part II may benefit from the reduced subscription tax of 0.01% provided that certain conditions are met. |
2. Specialized Investment Funds (SIFs)
| New regime introduced by the law of 21 July 2023 | Previous regime under SIF Law | |
|---|---|---|
| Eligibility of well-informed investor | The investment threshold has been lowered to EUR 100,000, and the list of entities authorized to certify the experience of other well-informed investors has been aligned. | The investment threshold was set at EUR 125,000. |
| Timeframe for reaching the minimum capital | The period for achieving subscribed capital has been extended to 24 months for SIFs. | The period for achieving subscribed capital was 12 months for SIFs. |
| Replacement of depositary | The depositary agreement must include prior notice provisions, and a replacement depositary must be appointed before the expiry of this notice period. During this transition period, outgoing depositaries are still required to safeguard the interests of investors. This change mitigates the risk of automatic de-listing, considering the necessary time for conducting due diligence and onboarding a new depositary. | A 2-month maximum period was previously foreseen to replace a depositary. |
| Suspension of subscription and/or redemption | Subscriptions and/or redemptions of a SICAV are prohibited: - for the period there is no depositary; - the depositary is in liquidation, declared bankrupt or undergoing a suspension of payments, an arrangement with its creditors or some other type of management supervision | The prohibition of subscription and/or redemption of a SICAV for the period during which there was no depositary or when the depositary was in liquidation, declared bankrupt or undergoing a suspension of payments, an arrangement with its creditors or some other type of management supervision was not foreseen under the previous regime. |
| Marketing | Marketing of AIFs in the form of a SIF to well-informed investors in Luxembourg is permissible (see further point E below). | Marketing of AIFs in the form of a SIF was permissible only to professional investors. |
| Tax | SIFs authorized as ELTIF are exempted from subscription tax as well when they are authorized as MMFs considering some certain conditions apply. |
3. Investment Companies in Risk Capital (SICARs)
| New regime introduced by the law of 21 July 2023 | Previous regime under SICAR Law | |
|---|---|---|
| Eligibility of well-informed investor | The investment threshold has been lowered to EUR 100,000, and the list of entities authorized to certify the experience of other well-informed investors has been aligned. | The investment threshold was set at EUR 125,000. |
| Timeframe for reaching the minimum capital | The period for achieving subscribed capital has been extended to 24 months for SICARs. | The period for achieving subscribed capital was 12 months for SICARs. |
| Replacement of depositary | The depositary agreement must include prior notice provisions, and a replacement depositary must be appointed before the expiry of this notice period. During this transition period, outgoing depositaries are still required to safeguard the interests of investors. This change mitigates the risk of automatic de-listing, considering the necessary time for conducting due diligence and onboarding a new depositary. | A 2-month maximum period was previously foreseen to replace a depositary. |
| Suspension of subscription and/or redemption | Subscriptions and/or redemptions of a SICAV are prohibited: - for the period there is no depositary; - the depositary is in liquidation, declared bankrupt or undergoing a suspension of payments, an arrangement with its creditors or some other type of management supervision. | The prohibition of subscription and/or redemption of a SICAV for the period during which there was no depositary or when the depositary was in liquidation, declared bankrupt or undergoing a suspension of payments, an arrangement with its creditors or some other type of management supervision was not foreseen under the previous regime. |
| Marketing | Marketing of AIFs in the form of a SICAR to well-informed investors in Luxembourg is permissible (see further point E below). | Marketing of AIFs in the form of a SICAR was permissible only to professional investors. |
| Tax | All in-kind contributions in a SICAR should be backed up by a valuation report drawn by an auditor. | Under the previous regime, there was no explicit obligation for the contributions in kind to be backed up by a valuation report drawn by an auditor. |
4. Reserved Alternative Investment Funds (RAIFs)
| New regime introduced by the law of 21 July 2023 | Previous regime under RAIF Law | |
|---|---|---|
| Eligibility of well-informed investor | The investment threshold has been lowered to EUR 100,000, and the list of entities authorized to certify the experience of other well-informed investors has been aligned. | The investment threshold was set at EUR 125,000. |
| Timeframe for reaching the minimum capital | The period for achieving subscribed capital has been extended to 24 months for RAIFs. | The period for achieving subscribed capital was 12 months for RAIFs. |
| Formation formalities | The formation formalities for RAIFs have been streamlined. The requirement for a Luxembourg notary to acknowledge the establishment and appointment of an external Alternative Investment Fund Manager (AIFM) within five business days has been eliminated for RAIFs established through a notarial deed, though it still applies to RAIFs established through a private deed. | Luxembourg notary shall acknowledge the establishment and appointment of an external Alternative Investment Fund Manager (AIFM) within five business days for RAIFs established through a notarial deed or a private deed. |
| Marketing | Marketing RAIFs to well-informed investors in Luxembourg is permissible (see further point E below). | Marketing of RAIFs was permissible only to professional investors. |
| Replacement of depositary | The depositary agreement must include prior notice provisions, and a replacement depositary must be appointed before the expiry of this notice period. During this transition period, outgoing depositaries are still required to safeguard the interests of investors. This change mitigates the risk of automatic de-listing, considering the necessary time for conducting due diligence and onboarding a new depositary. | A 2-month maximum period to replace a depositary was previously foreseen. |
| Suspension of subscription and/or redemption | Subscriptions and/or redemptions of a SICAV are prohibited: - for the period there is no depositary; - the depositary is in liquidation, declared bankrupt or undergoing a suspension of payments, an arrangement with its creditors or some other type of management supervision | The prohibition of subscription and/or redemption of a SICAV for the period during which there was no depositary or when the depositary was in liquidation, declared bankrupt or undergoing a suspension of payments, an arrangement with its creditors or some other type of management supervision was not foreseen under the previous regime. |
| Tax | RAIFs authorized as ELTIF are exempted from subscription tax. |
5. Alternative Investment Fund Managers (AIFMs)
| New regime introduced by the law of 21 July 2023 | Previous regime under AIFM Law | |
|---|---|---|
| Tied Agents | Authorized alternative investment fund managers are permitted to utilize tied agents as defined by article 1, point 1 of the law of 5 April 1993 on the financial sector. Where an AIFM decides to use tied agents, the AIFM shall, within the limits of the activities permitted under this law, comply with the same rules as those applicable to investment firms under Article 37-8 of the amended law of 5 April 1993 on the financial sector. | The appointment of tied agents was foreseen under the previous regime for pre-marketing purposes. |
| Marketing | AIFMs may market shares/units of AIF SIFs, RAIFs and AIF SICARs to well-informed investors established or residing in Luxembourg even if they do not fall in the scope of the definition of a professional investor. | AIFMs may market shares/units of AIF SIFs, RAIFs and AIF SICARs only to professional investors. |
Should you have any inquiries or require expert guidance pertaining to the information provided, our investment management team is available to assist you.
Bill of Law 8183 adopted: Examining the impact on Luxembourg's RAIF, SIF, SICAR, AIFM, and UCI Laws
Luxembourg has taken a significant stride towards modernizing its investment fund laws with the recent adoption of Bill 8183 by the Luxembourg Parliament. This bill introduces amendments to several pivotal fund laws, including the Law of 2010 on Undertakings for Collective Investment (UCI Law), the Law of 2007 on Specialized Investment Funds (SIF Law), the Law of 2004 on Investment Companies in Risk Capital (SICAR Law), the Law of 2013 on Alternative Investment Fund Managers (AIFM Law), and the Law of 2016 on Reserved Alternative Investment Funds (RAIF Law). These amendments are designed to update and strengthen the country’s fund-related regulations, bolstering the competitiveness and attractiveness of Luxembourg’s financial centre.
On March 24, 2023, a bill of law proposing amendments to the Luxembourg fund laws was submitted to the Luxembourg Parliament. The first constitutional vote, held on July 11, 2023, resulted in the adoption of Bill 8183, with an overwhelming majority of 55 votes in favour out of 60. To expedite the implementation of the law, a request was made to dispense with the second vote, which was accepted on 14 July with unanimity.
The adopted amendments encompass several significant changes, including:
Definition of “Well-informed Investor” and marketing RAIFs to well-informed investors in Luxembourg
The definition of a “well-informed investor” has been harmonized across the SIF, SICAR, and RAIF Laws as well as the possibility to market shares or units of such vehicles to retail investors within the meaning of “well-informed investor”. The investment threshold has been lowered to EUR 100,000, and the list of entities authorized to certify the experience of other well-informed investors has been aligned.
Time limit for reaching minimum capital
The period for achieving subscribed capital has been extended to 24 months for SICARs, SIFs, and RAIFs and to 12 months for UCIs (Part II). This extension grants fund managers increased flexibility in meeting the minimum capital requirement.
Harmonization of legal form for Part II UCIs
The available legal forms for Part II SICAVs have been aligned with the legal forms permitted under the SIF, SICAR, and RAIF Laws. This harmonization ensures consistency among various types of investment funds.
Simplification for RAIFs
The formation formalities for RAIFs have been streamlined. The requirement for a Luxembourg notary to acknowledge the establishment and appointment of an external Alternative Investment Fund Manager (AIFM) within five business days has been eliminated for RAIFs established through a notarial deed, though it still applies to RAIFs established through a private deed. Furthermore, the amendment clarifies that marketing RAIFs to well-informed investors in Luxembourg is permissible.
Amendments to the AIFM Law
Authorized managers of alternative investment funds are now permitted to utilize tied agents, as defined by the 1993 law on the financial sector. This amendment provides them with additional operational flexibility.
Replacement of a depositary
Previously, SICARs, SIFs, UCITS, and Part II funds had an automatic two-month period to replace a depositary in the event of resignation or termination. However, under the new rules, this automatic de-listing provision has been eliminated. Instead, the depositary agreement must now include prior notice provisions, and a replacement depositary must be appointed before the expiry of this notice period. During this transition period, outgoing depositaries are still required to safeguard the interests of investors. This change mitigates the risk of automatic de-listing, considering the necessary time for conducting due diligence and onboarding a new depositary.
Main tax amendments
The newly introduced exemptions from the subscription tax, as part of the Bill of Law 8183, offer benefits to specific structures. These include (i) Part II UCIs, SIFs, RAIFs and their respective sub-funds, provided they are authorized as ELTIFs under the ELTIF Regulation, and (ii) UCITS/Part II UCIs and their sub-funds that cater specifically to investors saving under a pan-European Personal Pension Product (PEPP) established as per the PEPP Regulation. This is a concerted effort to stimulate the creation and growth of ETIFs and PEPPs.
The adoption of these amendments by the Luxembourg Parliament signifies a momentous development in the country’s investment fund legislation. The reforms aim to modernize and enhance the toolbox for Luxembourg funds, fostering a more consistent and practical approach. These changes not only strengthen the regulatory framework but also contribute to the competitiveness and allure of Luxembourg’s financial center. The anticipation is that the legislation will soon be published in the Luxembourg Official Gazette. It will become effective on the fourth day following its publication in the Luxembourg Official Gazette.
Should you have any inquiries or require expert guidance pertaining to the information provided, our investment management team is available to assist you. Please feel free to contact us.
Luxembourg Fund Law Reforms: Key proposed changes to RAIF, SIF, SICAR, AIFM, and UCI Laws
On March 24, 2023, a bill of law was submitted to the Luxembourg Parliament, proposing amendments to the Luxembourg fund laws, namely the Law of 2010 on UCIs (UCI Law), the Law of 2007 on SIFs (SIF Law), the Law of 2004 on SICARs (SICAR Law), the Law of 2013 on AIFMs (AIFM Law), and the Law of 2016 on RAIFs (RAIF Law).
Below is a summary of the main changes:
Definition of “Well-informed Investor”
The proposed amendments aim to harmonize the “well-informed investor” definition in the SIF, SICAR, and RAIF Laws by reducing the investment threshold to EUR 100,000 and aligning the list of entities that can certify the experience of other well-informed investors.
Time Limit for Reaching Minimum Capital
The proposed amendments suggest increasing the subscribed capital time limit for SICARs, SIFs, and RAIFs to 24 months, while for Part II funds, the time limit is proposed to be extended to 12 months.
Harmonization of Legal Form for Part II UCI
The proposed amendments aim to align the available legal forms for Part II SICAVs with the legal forms permitted under the SIF, SICAR, and RAIF Laws.
Simplification for RAIFs
The proposed amendments also seek to simplify the formation formalities for RAIFs where a RAIF is set up by virtue of articles of association, by eliminating the requirement for a Luxembourg notary to acknowledge the establishment and appointment of an external AIFM within five business days if established through notarial deed, although this requirement still applies to RAIFs established through private deed. Moreover, it clarifies that marketing RAIFs to well-informed investors in Luxembourg is permitted.
Amendments to the AIFM Law
The proposed amendments would allow authorized alternative investment fund managers to have recourse to tied agents as defined by the 1993 financial sector law.
In conclusion, the proposed amendments represent a significant step towards modernizing and improving Luxembourg’s fund toolbox by providing a more consistent and practical approach. It remains to be seen how the proposed amendments will be received by the Luxembourg Parliament and whether they will ultimately be adopted. The bill of law is subject to the lawmaking procedure and may undergo further changes. We will keep you updated on the evolution of the Luxembourg funds rules.
If you have any questions regarding the information above, our investment management team is here to help. Please do not hesitate to contact us for expert guidance.
New reporting obligations for RAIFs and unregulated AIFs - Update of the CRS FAQ by the Luxembourg tax administration
Key takeaway
RAIFs and unregulated AIFs (e.g. SCSp and SCS) are now considered reportable financial institutions since they can no longer benefit from the exempt CIV status. They must file a (nil) report by 30 June 2022 to avoid penalties.
Introduction
On 4 April 2022, the Luxembourg direct tax administration (“ACD”) updated its frequently asked questions (“FAQ”) on the common reporting standard (“CRS”). Such FAQ now includes two new questions, providing a list of Investment Entities (I) and a clarification relating to the scope of the exempt Collective Investment Vehicle (“exempt CIV”) status (II). They are important, in particular, for reserved alternative investment funds (“RAIFs”) and unregulated alternative investment funds (“AIFs”). As a reminder, CRS is an automatic exchange of information relating to financial accounts in tax matters with the Member States of the European Union and the other partner jurisdictions of Luxembourg as implemented by the amended law of 18 December 2015 relating to the automatic exchange of information in tax matters (“CRS Law”). The CRS Law requires Reporting Financial Institutions (“RFIs”) to declare some information in relation to certain accounts and the holders of such accounts. The RFIs are defined as all financial institutions which are not non-reporting financial institutions (“NRFIs”). One element of the definition of the NRFIs is the exempt CIV status. Therefore, such exempt CIVs do not have to report to the ACD concerning CRS matters. The updated FAQ narrows the scope of the exempt CIV status, which was interpreted as including RAIFs and other unregulated AIFs until now.
Please find below the two Q&A of the ACD in the updated FAQ on CRS.
I) A non-exhaustive list of Investment Entities (Q 2.3)
Except in special circumstances, the following entities are, in principle, considered Investment Entities:
– any undertaking for collective investment subject to Part I or II of the amended law of 17 December 2010 relating to undertakings for collective investment;
– any specialized investment fund subject to the amended law of 13 February 2007 relating to specialized investment funds;
– any venture capital company governed by the amended law of 15 June 2004 relating to venture capital companies (SICAR);
– any securitisation undertaking subject to the authorisation and supervision of the Commission de Surveillance du Secteur Financier (the “CSSF”) in accordance with the amended law of 22 March 2004 relating to securitisation;
– any RAIF falling within the scope of the amended law of 23 July 2016 relating to reserved alternative investment funds;
– any AIF whose management falls within the scope of the amended law of 12 July 2013 relating to alternative investment fund managers;
– any pension fund governed by the amended law of 13 July 2005 relating to institutions for occupational retirement provision in the form of SEPCAV and ASSEP;
– any pension fund governed by the amended Grand-Ducal Regulation of 31 August 2000 implementing Article 26, paragraph 3, of the amended law of 6 December 1991 on the insurance sector and relating to pension funds subject to the prudential supervision of the Commissariat aux assurances;
– any management company subject to part IV of the amended law of 17 December 2010 relating to undertakings for collective investment;
– any manager of alternative investment funds governed by the amended law of 12 July 2013 relating to managers of alternative investment funds; and
– any investment firm governed by the amended law of 5 April 1993 relating to the financial sector which carries out any of the following activities: (i) execution of orders on behalf of clients, (ii) portfolio management.
II) Unregulated entities such as RAIFs and other unregulated AIFs and the exempt CIV status (Q 2.4)
The ACD indicates in the FAQ that unregulated entities can no longer benefit from the exempt CIV status, as only entities directly supervised by the CSSF may opt for this status if the other applicable conditions are fulfilled.
As a result of the answers mentioned above, the RAIFs and the unregulated AIFs should now submit every year a nil report to the ACD if there is no CRS reportable account. Indeed, RAIFs and unregulated AIFs may not qualify as NRFI anymore. Therefore, RAIFs and unregulated AIFs qualifying as RFI must respect the reporting and due diligence CRS obligations. They should review their CRS qualifications and applicable CRS reporting obligations.
Based on the fact that neither the CRS law nor the ACD refer to the legal form of the entities, the same reasoning applies to unregulated AIFs under the form of a common limited partnership (société en commandite simple – SCS) or a special limited partnership (société en commandite spéciale – SCSp). RAIFs and unregulated AIFs should, in principle, have no CRS reportable accounts. If so, a nil report should be filed by 30 June 2022 for the two fiscal years 2020 and 2021 in order to avoid any penalties.
There are two types of penalties:
– a Luxembourg RFI omitting to comply with due diligence rules or to introduce procedures in view of reporting is liable to a penalty up to EUR 250,000; and
– a Luxembourg RFI omitting to file the required report or if it files a late, incomplete or inaccurate report, it may be liable to a penalty of 0,5% of the amounts that should have been reported, with a minimum of EUR 1,500.